My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 4: Analysis of Financial Statements

Practice each question, then open the answer or worked solution.

Numerical Questions for NCERT Accountancy Solutions Part 2 Class 12 Chapter 4

6 questions
Q1Written answer

Following are the balance sheets of Alpha Ltd. as on March 31st, 2016, and 2017:

Particulars 2016
₹.
2017
₹.
I. Equity and Liabilities
Equity share capital 2,00,000 4,00,000
Reserves and surplus 1,00,000 1,50,000
Long-term borrowings 2,00,000 3,00,000
Short-term borrowings 50,000 70,000
Trade payables 30,000 60,000
Short-term provisions 20,000 10,000
Other current liabilities 20,000 30,000
Total 6,20,000 10,20,000
II. Assets
Fixed assets 2,00,000 5,00,000
Non-current investments 1,00,000 1,25,000
Current investments 60,000 80,000
Inventories 1,35,000 1,55,000
Trade receivables 60,000 90,000
Short term loans and advances 40,000 60,000
Cash at bank 25,000 10,000
Total 6,20,000 10,20,000
Show solutionHide solution
Worked solution
Comparative Balance Sheet

as on March 31, 2016, and 2017

Particulars 2016

(₹)

2017

(₹)

Absolute Change Percentage Change
I. Equity and Liabilities
1. Shareholder’s Fund
a. Equity Share Capital 2,00,000 4,00,000 2,00,000 100
b. Reserves and Surplus 1,00,000 1,50,000 50,000 50
2. Non-Current Liabilities
a. Long Term Borrowings 2,00,000 3,00,000 1,00,000 50
3. Current Liabilities
a. Short Term Borrowings 50,000 70,000 20,000 40
b. Trade Payables 30,000 60,000 30,000 100
c. Short Term Provisions 20,000 10,000 (10,000) (50)
d. Other Current Liabilities 20,000 30,000 10,000 50
Total 6,20,000 10,20,000 4,00,000 64.5
II. Assets
1. Non-Current Assets
a. Fixed Assets 2,00,000 5,00,000 3,00,000 150
b. Non-current Investments 1,00,000 1,25,000 25,000 25
2. Current Assets 
a. Current Investments 60,000 80,000 20,000 33.3
b. Inventories 1,35,000 1,55,000 20,000 14.8
c. Trade Receivables 60,000 90,000 30,000 50
d. Short Term Loans and Advances 40,000 60,000 20,000 50
e. Cash and Cash Equivalents 25,000 10,000 (15,000) (60)
Total 6,20,000 10,20,000 4,00,000 64.5
Q2Written answer

Following are the balance sheets of Beta Ltd. as on March 31st, 2016 and 2017:

Particulars 2017
₹.
2016
₹.
I. Equity and Liabilities
Equity share capital 4,00,000 3,00,000
Reserves and surplus 1,50,000 1,00,000
Loan from IDBI 3,00,000 1,00,000
Short-term borrowings 70,000 50,000
Trade payables 60,000 30,000
Short-term provisions 10,000 20,000
Other current liabilities 1,10,000 1,00,000
Total 11,00,000 7,00,000
II. Assets
Fixed assets 4,00,000 2,20,000
Non-current investments 2,25,000 1,00,000
Current investments 80,000 60,000
Stock 1,05,000 90,000
Trade receivables 90,000 60,000
Short term loans and advances 1,00,000 85,000
Cash and cash equivalents 1,00,000 85,000
Total 11,00,000 7,00,000
Show solutionHide solution
Worked solution
Comparative Balance Sheet

as on March 31, 2016, and 2017

Particulars 2016

(₹)

2017

(₹)

Absolute Change Percentage Change
I. Equity and Liabilities
1. Shareholder’s Fund
 a. Equity Share Capital 3,00,000 4,00,000 1,00,000 33.3
 b. Reserves and Surplus 1,00,000 1,50,000 50,000 50
2. Non-Current Liabilities
a. Long Term Borrowings

(Loan from IDBI)

1,00,000 3,00,000 2,00,000 200
3. Current Liabilities
 a. Short Term Borrowings 50,000 70,000 20,000 40
 b. Trade Payables 30,000 60,000 30,000 100
 c. Short Term Provisions 20,000 10,000 (10,000) (50)
 d. Other Current Liabilities 1,00,000 1,10,000 10,000 10
Total 7,00,000 11,00,000 4,00,000 57.14
II. Assets
1. Non-Current Assets
 a. Fixed Assets 2,20,000 4,00,000 1,80,000 81.8
 b. Non-current Investments 1,00,000 2,25,000 1,25,000 125
2. Current Assets
 a. Current Investments 60,000 80,000 20,000 33.3
 b. Inventories (Stock) 90,000 1,05,000 15,000 16.6
 c. Trade Receivables 60,000 90,000 30,000 50
 d. Short Term Loans and Advances 85,000 1,00,000 15,000 17.65
 e. Cash and Cash Equivalents 85,000 1,00,000 15,000 17.65
Total 7,00,000 11,00,000 4,00,000 57.14
Q3Written answer

Prepare a Comparative Income Statement from the following information:

Particulars 2016-17
₹.
2015-16
₹.
Freight Outward 20,000 10,000
Wages (office) 10,000 5,000
Manufacturing Expenses 50,000 20,000
Stock adjustment (60,000) 30,000
Cash purchases  80,000 60,000
Credit purchases  60,000 20,000
Returns inward  8,000 4,000
Gross profit (30,000) 90,000
Carriage outward 20,000 10,000
Machinery 3,00,000 2,00,000
Charge 10% depreciation on machinery 10,000 5,000
Interest on short-term loans 20,000 20,000
10% debentures 20,000 10,000
Profit on sale of furniture 20,000 10,000
Loss on sale of the office car 90,000 60,000
Tax rate 40% 50%
Show solutionHide solution
Worked solution
Comparative Income Statement

for the year ended March 31, 2016, and 2017

Particulars Note

No.

2015-16

(₹)

2016-17

(₹)

Absolute 

Change
(₹)

Percentage

Change

1. Revenue from Operations 2,16,000 92,000 (1,24,000) (57.4)
2. Other Income 10,000 20,000 10,000 100
3. Total Revenue (1 + 2) 2,26,000 1,12,000 (1,14,000) (50.44)
4. Expenses
a. Purchases of Stock-in-Trade 80,000 1,40,000 60,000 75
b. Change in Inventories 30,000 (60,000) (90,000) (300)
c. Employee Benefit Expenses 5,000 10,000 5,000 100
d. Finance Costs 21,000 22,000 1,000 4.54
e. Depreciation and Amortisation Expenses 5,000 10,000 5,000 100
f. Other Expenses 80,000 1,30,000 50,000 62.5
 Total Expenses 2,21,000 2,52,000 31,000 14.03
5. Profit before Tax (3 – 4) 5,000 (1,40,000) (83,000) 16.6
     Less: Income Tax 2,500 – (2,500) (100)
6. Profit After Tax 2,500 (1,40,000) (1,37,500) 55

Working Notes:

1. Calculation of Net Sales

Net Sales = Cost of Goods Sold + Gross Profit – Sales Return

or, Net Sales = Purchases + Manufacturing Expenses + Change in Inventory + Gross Profit – Sales Return

Net Sales (2016) = 80,000 + 20,000 +30,000 + 90,000 – 4,000 = ₹ 2, 16,000

Net Sales (2017) = 1, 40,000 + 50,000 – 60,000 – 30,000 – 80,000 = ₹ 92,000

2. Calculation of Finance Cost

Finance Cost = Interest on short-term loans + Interest on 10% Debentures

Finance Cost (2016) = 20,000 + 1,000 = ₹ 21,000

Finance Cost (2017) = 20,000 + 2,000 = ₹ 22,000

3. Calculation of Other Expenses

Other Expenses = Freight Outward + Carriage Outward + Loss on sale of the office car

Other Expenses (2016) = 10,000 + 10,000 + 60,000 = ₹ 80,000

Other Expenses (2017) = 20,000 + 20,000 + 90,000 = ₹ 1, 30,000

Q4Written answer

Prepare a Comparative Income Statement from the following information:

Particulars 2015-16
₹.
2016-17
₹.
Manufacturing expenses 35,000 80,000
Opening stock 30,000 60% of closing stock
Sales 9,60,000 4,50,000
Returns outward 4,000 (out of credit purchase) 6,000 (out of cash purchase)
Closing stock 150% of opening stock 1,00,000
Credit purchases 1,50,000 150% of cash purchase
Cash purchases 80% of credit purchases 40,000
Carriage outward 10,000 30,000
Building 1,00,000 2,00,000
Depreciation on building 20% 10%
Interest on bank overdraft 5,000 –
10% debentures 2,00,000 20,00,000*
Profit on sale of copyright 10,000 20,000
Loss on sale of personal car 10,000 20,000
Other operating expenses 20,000 10,000
Tax rate 50% 40%
Show solutionHide solution
Worked solution

*There is a misprint in the book; this should be 2,00,000

Comparative Income Statement

for the years ended March 31, 2016, and 2017

Particulars Note

 No.

2015-16

(₹)

2016-17

(₹)

Absolute 

Change
(₹)

Percentage

Change 

1. Revenue from Operations 9,60,000 4,50,000 (5,10,000) (53.13)
2. Other Income 10,000 20,000 10,000 100
3. Total Revenue (1 + 2) 9,70,000 4,70,000 (5,00,000) (51.55)
4. Expenses
a. Purchases of Stock-in-Trade 2,66,000 94,000 (1,72,000) (64.7)
b. Change in Inventories (15,000) (40,000) (55,000) (366.7)
c. Finance Costs 25,000 20,000 (5,000) (20)
d. Depreciation and Amortisation Expenses 20,000 20,000 – –
e. Other Expenses 30,000 40,000 10,000 33.33
 Total Expenses 3,26,000 1,34,000 (1,92,000) 58.90
5. Profit before Tax (3 – 4) 6,44,000 3,36,000 (3,08,000) 47.83
     Less: Income Tax 3,22,000 1,34,400 (1,87,600) 58.26
6. Profit After Tax 3,22,000 2,01,600 1,20,400 37.39

Working Notes:

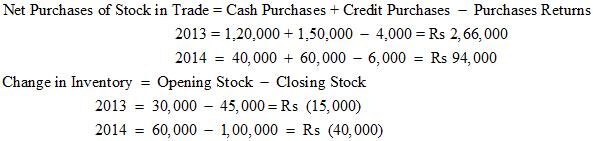
1. Calculation of Net Purchases and Change in Inventory

Class 12 Chp 4-6

2. Calculation of Finance Cost

Finance Cost = Interest on Bank Overdraft + Interest on Debentures

Finance Cost (2016) = 5,000 + 20,000 = ₹ 25,000

Finance Cost (2017) = 0 + 20,000 = ₹ 20,000

3. Calculation of Other Expenses

Other Expenses = Carriage outward + other operating expenses

Other Expenses (2016) = 10,000 + 20,000 = ₹ 30,000

Other Expenses (2017) = 30,000 + 10,000 = ₹ 40,000

Q5Written answer

Prepare a common size statement of profit and loss of Shefali Ltd. with the help of the following information:

Particulars 2015-16
(₹)
2016-17
(₹)
Revenue from operations  6,00,000 8,00,000
Indirect expense  25% of gross profit 25% of gross profit
Cost of revenue from operations  4,28,000 7,28,000
Other incomes 10,000 12,000
Income tax 30%  30%
Show solutionHide solution
Worked solution
Common Size Income Statement

for the years ended March 31, 2016, and 20174

Particulars Note

No.

2015-16

(₹)

2016-17

(₹)

Percentage of

Sales

2015-16 2016-17
1. Revenue from Operations 6,00,000 8,00,000 100 100
2. Other Income 10,000 12,000 1.67 1.5
3. Total Revenue (1 + 2) 6,10,000 8,12,000 101.67 101.5
4. Expenses
a. Cost of Revenue from Operations (COGS) 4,28,000 7,28,000 71.33 91
b. Other Expenses 43,000 18,000 7.17 2.25
 Total Expenses 4,71,000 7,46,000 78.5 93.25
5. Profit before Tax (3 – 4) 1,39,000 66,000 23.167 8.25
     Less: Income Tax (41,700) (19,800) 5.35
6. Profit After Tax 97,300 46,200 16.22 5.775

Working Notes:

1. Calculation of expenses

Other Expenses = Indirect Expenses = % of Gross Profit

Gross Profit = Net Sales −- Revenue from Operations

For 2016, Gross Profit = ₹(6,00,000 −- 4,28,000) = ₹1,72,000

For 2017, Gross Profit = ₹(8,00,000 −- 7,28,000) = ₹72,000

2016=1,72,000×25%=₹43,000

2017=72,000×25%=₹18,000

2016=1, 72,000×25%=₹43,000

2017=72,000×25%=₹18,000

Q6Written answer

Prepare a common size balance sheet from the following balance sheet of Aditya Ltd. and Anjali Ltd.:

Particulars Aditya Ltd.
₹.
Anjali Ltd.
₹.
I. Equity and Liabilities
a) Equity share capital 6,00,000 8,00,000
b) Reserves and surplus 3,00,000 2,50,000
c) Current liabilities 1,00,000 1,50,000
Total 10,00,000 12,00,000
II. Assets
a) Fixed assets  4,00,000 7,00,000
b) Current assets  6,00,000 5,00,000
Total 1,00,0000* 12,00,000
Show solutionHide solution
Worked solution

*The total liabilities side must be equal to the total assets side; therefore, it should be 10,00,000.

Common Size Balance Sheet 
Particulars Aditya Ltd.

(₹)

Anjali Ltd. 

(₹)

% of Total 
Aditya Ltd. Anjali Ltd.
I. Equity and Liabilities
1. Shareholder’s Fund
a. Equity Share Capital 6,00,000 8,00,000 60 66.67
b. Reserves and Surplus 3,00,000 2,50,000 30 20.83
2. Current Liabilities 1,00,000 1,50,000 10 12.5
Total 10,00,000 12,00,000 100 100
II. Assets
1. Non-Current Assets
a. Fixed Assets 4,00,000 7,00,000 40 58.33
 2. Current Assets 6,00,000 5,00,000 60 41.67
Total 10,00,000 12,00,000 100 100

Concepts covered in this chapter are listed below:

  • Meaning of financial analysis
  • Significance of financial analysis
  • Trend analysis
  • Tools of financial analysis
  • Limitations of financial analysis
Conclusion