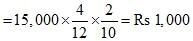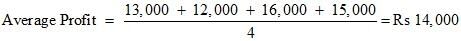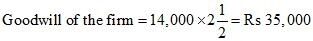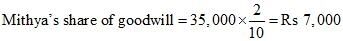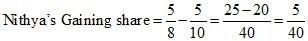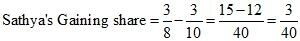The Balance Sheet of Rajesh, Pramod and Nishant, who were sharing profits in proportion to their capitals, stood as on March 31, 2015:
| Books of Rajesh, Pramod and Nishant
Balance Sheet as on March 31, 2015 |
||||||
| Liabilities | Amount
₹ |
Assets | Amount
₹ |
|||
| Bills Payable | 6,250 | Factory Building | 12,000 | |||
| Sundry Creditors | 10,000 | Debtors | 10,500 | |||
| Reserve Fund | 2,750 | Less: Reserve | 500 | 10,000 | ||
| Capital Accounts: | Bills Receivable | 7,000 | ||||
| Rajesh | 20,000 | Stock | 15,500 | |||
| Pramod | 15,000 | Plant and Machinery | 11,500 | |||
| Nishant | 15,000 | 50,000 | Bank Balance | 13,000 | ||
| 69,000 | 69,000 | |||||
Pramod retired on the date of the Balance Sheet, and the following adjustments were made:
a) Stock was valued at 10% less than the book value.
b) Factory buildings were appreciated by 12%.
c) Reserve for doubtful debts be created up to 5%.
d) Reserve for legal charges to be made at ₹ 265.
e) The goodwill of the firm be fixed at ₹ 10,000.
f) The capital of the new firm be fixed at ₹ 30,000. The continuing partners decide to keep their capital in the new profit-sharing ratio of 3:2.
Pass journal entries and prepare the balance sheet of the reconstituted firm after transferring the balance from Pramod’s Capital account to his loan account.
Show solutionHide solution
| Journal | |||||||
| Date | Particulars | L.F. | Amount
₹ |
Amount
₹ |
|||
| 2015 | |||||||
| Mar. 31 | Revaluation A/c | Dr. | 1,840 | ||||
| To Stock A/c | 1,550 | ||||||
| To Reserve for Doubtful Debts A/c | 25 | ||||||
| To Reserve for Legal Charges A/c | 265 | ||||||
| (Assets and Liabilities are revalued) | |||||||
| Mar. 31 | Factory Building A/c | Dr. | 1,440 | ||||
| To Revaluation A/c | 1,440 | ||||||
| (Factory Building appreciated) | |||||||
| Mar. 31 | Rajesh’s Capital A/c | Dr. | 160 | ||||
| Pramod’s Capital A/c | Dr. | 120 | |||||
| Nishant’s Capital A/c | Dr. | 120 | |||||
| To Revaluation A/c | 400 | ||||||
| (Loss on Revaluation adjusted to Partners’ Capital Account) | |||||||
| Mar. 31 | Rajesh’s Capital A/c | Dr. | 2,000 | ||||
| Nishant’s Capital A/c | Dr. | 1,000 | |||||
| To Pramod Capital’s A/c | 3,000 | ||||||
| (Pramod’s share of goodwill adjusted to Rajesh’s and Nishant’s Capital Account in their gaining ratio) | |||||||
| Mar. 31 | Reserve Fund A/c | Dr. | 2,750 | ||||
| To Rajesh’s Capital A/c | 1,100 | ||||||
| To Pramod’s Capital A/c | 825 | ||||||
| To Nishant’s Capital A/c | 825 | ||||||
| (Reserve Fund distributed all the partners) | |||||||
| Mar. 31 | Pramod’s Capital A/c | Dr. | 18,705 | ||||
| To Pramod’s Loan A/c | 18,705 | ||||||
| (Pramod’s Capital was transferred to his Loan Account) | |||||||
| Mar. 31 | Rajesh’s Capital A/c | Dr. | 940 | ||||
| Nishant’s Capital A/c | Dr. | 2,705 | |||||
| To Rajesh’s Current A/c | 940 | ||||||
| To Nishant’s Current A/c | 2,705 | ||||||
| (Excess in Capital Account is transferred to Current Account) | |||||||
| Parters’ Capital Account | |||||||||
| Dr. | Cr. | ||||||||
| Particulars | Rajesh | Pramod | Nishant | Particulars | Rajesh | Pramod | Nishant | ||
| Revaluation (Loss) | 160 | 120 | 120 | Balance b/d | 20,000 | 15,000 | 15,000 | ||
| Pramod’s Capital A/c | 2,000 | 1,000 | Reserve Fund | 1,100 | 825 | 825 | |||
| Pramod’s Loan A/c | 18,705 | Rajesh’s Capital A/c | 2,000 | ||||||
| Rajesh’s Current A/c | 940 | Nishant’s Capital A/c | 1,000 | ||||||
| Nishant’s Current A/c | 2,705 | ||||||||
| Balance c/d | 18,000 | 12,000 | |||||||
| 21,100 | 18,825 | 15,825 | 21,100 | 18,825 | 15,825 | ||||
| Balance Sheet as on March 31, 2015 | ||||||
| Liabilities | Amount
₹ |
Assets | Amount
₹ |
|||
| Bills Payable | 6,250 | Plant and Machinery | 11,500 | |||
| Sundry Creditors | 10,000 | Debtors | 10,500 | |||
| Reserve for Legal Charges | 265 | Less: Reserve | (525) | 9,975 | ||
| Pramod’s Loan | 18,705 | Bills Receivable | 7,000 | |||
| Current Account: | Stock | 15,500 | ||||
| Rajesh | 940 | Less: 10% Depreciation | (1,550) | 13,950 | ||
| Nishant | 2,705 | 3,645 | ||||
| Capital Account: | Factory Building | 12,000 | 13,440 | |||
| Rajesh | 18,000 | Add: 12% Appreciation | 1,440 | |||
| Nishant | 12,000 | 30,000 | Bank Balance | 13,000 | ||
| 68,865 | 68,865 | |||||
Working Notes:
1) Pramod’s share of goodwill = Total goodwill of the firm × Retiring partner’s share =
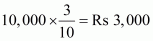
2) Gaining Ratio = New Ratio − Old Ratio
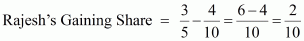
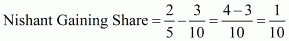
Gaining Ratio between Rajesh and Nishant = 2:1
NOTE: In the above solution, in order to adjust the capital of remaining partners in the new firm according to their new profit-sharing ratio, the surplus or the deficit of the Capital Account is transferred to their Current Account. But, in order to match the answer with that given in the book, the surplus or the deficit amount of the Partners’ Capital Account will either be withdrawn or brought in by the old partners. This treatment will be shown in the Partners’ Capital itself, and no need to transfer the surplus or deficit capital balance to their Current Accounts. The following Journal entry is passed for recording the withdrawal of surplus capital by the partners.
If existing partners withdraw their excess capital,
Journal entry will be as follows:
| Rajesh’s Capital A/c | Dr. | 940 | |
| Nishant’s Capital A/c | Dr. | 2,705 | |
| To Bank A/c | 3,645 | ||
| (Surplus Capital withdrawn) | |||
| Balance Sheet as on March 31, 2015 | ||||||
| Liabilities | Amount
₹ |
Assets | Amount
₹ |
|||
| Bills Payable | 6,250 | Plant and Machinery | 11,500 | |||
| Sundry Creditors | 10,000 | Debtors | 10,500 | |||
| Reserve for Legal Charges | 265 | Less: Reserve | (525) | 9,975 | ||
| Pramod’s Loan | 18,705 | Bills Receivable | 7,000 | |||
| Capital: | Stock | 15,500 | ||||
| Rajesh | 18,000 | Less: 10% Depreciation | (1,550) | 13,950 | ||
| Nishant | 12,000 | 30,000 | ||||
| Factory Building | 12,000 | |||||
| Add: 12% Appreciation | 1,440 | 13,440 | ||||
| Bank Balance | 9,355 | |||||
| 65,220 | 65,220 | |||||
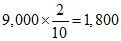
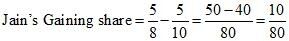
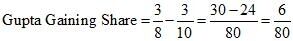
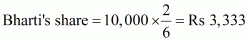
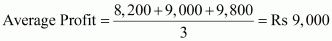
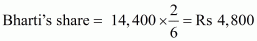
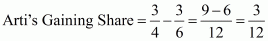
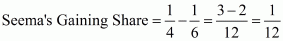
 times the average profits of the last four years. The profits for four years were: in 2011-12, ₹ 13,000; in 2012-13, ₹ 12,000; in 2013-14, ₹ 16,000; and in 2014-15, ₹ 15,000.