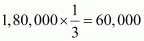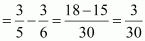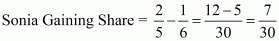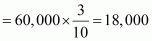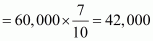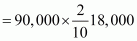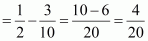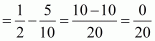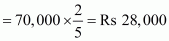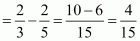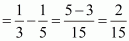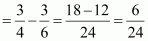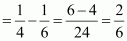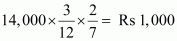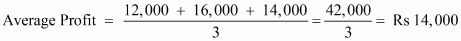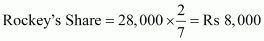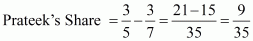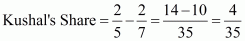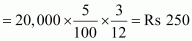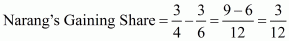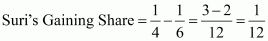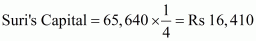| Pammy’s Capital Account |
|
| Dr. |
Cr. |
|
| Particulars |
Amount
₹ |
Particulars |
Amount
₹ |
| Drawings |
10,000 |
Balance b/d |
40,000 |
| Pammy Executor’s A/c |
75,400 |
Profit and Loss (Suspense) |
3,000 |
|
|
Puneet’s Capital A/c |
15,000 |
|
|
Pankaj’s Capital A/c |
15,000 |
|
|
Interest on Capital |
2,400 |
|
|
Reserve |
10,000 |
|
85,400 |
|
85,400 |
|
|
|
|
|
|
|
|
|
|
| Pammy’s Executor Account |
|
| Dr. |
Cr. |
|
| Date |
Particulars |
J.F. |
Amount
₹ |
Date |
Particulars |
J.F. |
Amount
₹ |
| 2017-18 |
|
|
|
2017-18 |
|
|
|
| Sep. 30 |
Bank |
|
15,400 |
Sep. 30 |
Pammy’s Capital A/c |
|
75,400 |
| Mar. 31 |
Balance c/d |
|
63,600 |
Mar. 31 |
Interest |
|
3,600 |
|
|
|
79,000 |
|
|
|
79,000 |
|
|
|
|
|
|
|
|
| 2018-19 |
|
|
|
2018-19 |
|
|
|
| Sep. 30 |
Bank |
|
22,200 |
April 01 |
Balance b/d |
|
63,600 |
|
(15,000+3,600+3,600) |
|
|
Sep. 30 |
Interest |
|
3,600 |
| Mar. 31 |
Balance c/d |
|
47,700 |
Mar. 31 |
Interest |
|
2,700 |
|
|
|
69,900 |
|
|
|
69,900 |
|
|
|
|
|
|
|
|
| 2019-20 |
|
|
|
2019-20 |
|
|
|
| Sep. 30 |
Bank |
|
20,400 |
April 01 |
Balance b/d |
|
47,700 |
| Mar. 31 |
Balance c/d |
|
31,800 |
Sep. 30 |
Interest |
|
2,700 |
|
|
|
|
Mar. 31 |
Interest |
|
1,800 |
|
|
|
52,200 |
|
|
|
52,200 |
|
|
|
|
|
|
|
|
| 2020-21 |
|
|
|
2020-21 |
|
|
|
| Sep. 30 |
Bank |
|
18,600 |
April 01 |
Balance b/d |
|
31,800 |
|
(15,000+1,800+1,800) |
|
|
Sep. 30 |
Interest |
|
1,800 |
| Mar. 31 |
Balance c/d |
|
15,900 |
Mar. 31 |
Interest |
|
900 |
|
|
|
34,500 |
|
|
|
34,500 |
|
|
|
|
|
|
|
|
| 2021-22 |
|
|
|
2021-22 |
|
|
|
| Sep. 30 |
Bank |
|
16,800 |
April 01 |
Balance b/d |
|
15,900 |
|
(15,000+900+900) |
|
|
Sep. 30 |
Interest |
|
900 |
|
|
|
16,800 |
|
|
|
16,800 |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Working Notes:
1) Pammy’s Share of Profit
Previous Year’s Profit × Proportionate Period × Share of Deceased Partner 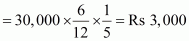
2) Pammy’s Share of Goodwill
Goodwill of the firm = Average Profit × Numbers of Year’s Purchase
Average Profit 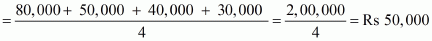
Goodwill of the Firm = 50,000 ´ 3 = ₹ 1,50,000
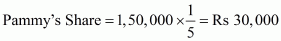
3) Gaining Ratio = New Ratio – Old Ratio
Puneet’s Share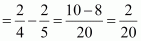
Pankaj’s Share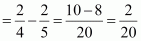
Gaining Ratio between Puneet and Pankaj = 2:2 or 1:1
4) Interest on Capital for 6 months, i.e. from April 1, 2007, to September 30, 2007
Amount of Capital × Rate of Interest × Period 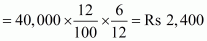
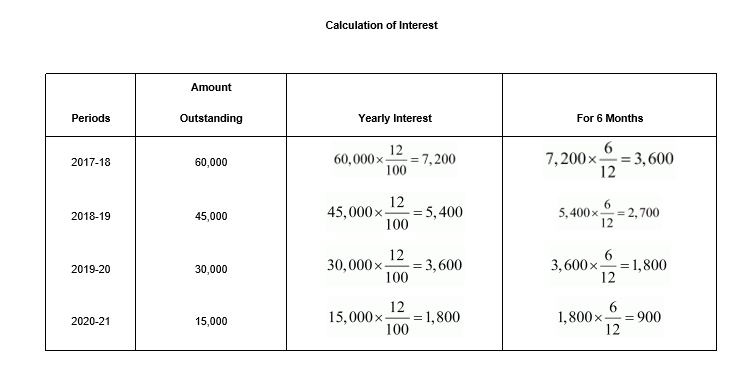
5) Interest Amount
The firm closes its books every year on March 31, while instalments to Pammy’s Executor are paid on September 30 every year.
Amount outstanding on 30 September = 75,400 – 15,400 = ₹ 60,000