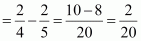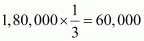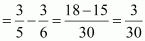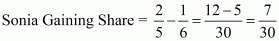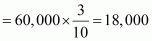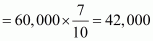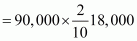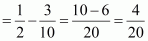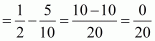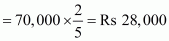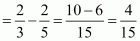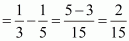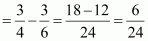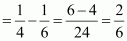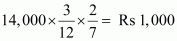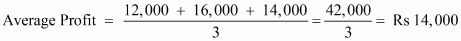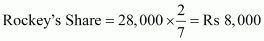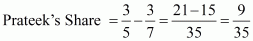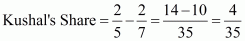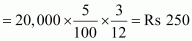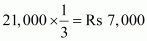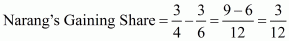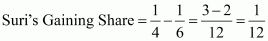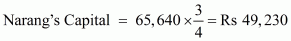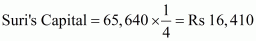My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 3: Reconstitution of a Partnership Firm – Retirement/Death of a Partner

Practice each question, then open the answer or worked solution.

Numerical Questions for NCERT Accountancy Solutions Class 12 Part 1 Chapter 4

14 questions
Q1Written answer

Aparna, Manisha and Sonia are partners sharing profits in the ratio of 3:2:1. Manisha retires, and the goodwill of the firm is valued at ₹ 1,80,000. Aparna and Sonia decided to share the future in the ratio of 3:2. Pass necessary Journal entries.


Show solutionHide solution
Worked solution
 Books of Aparna and Sonia


Journal


Date Particulars L.F. Amount

₹

Amount

₹

Aparna’s Capitals A/c Dr. 18,000
Sonia’s Capital A/c Dr. 42,000
To Manisha’s Capital A/c 60,000
(Manisha’s share of goodwill adjusted to Aparna’s and

Sonia’s Capital Account in their gaining ratio )

Working Notes:

i. Manisha’s share in goodwill:

Total goodwill of the firm × Retiring partner’s share =
Chp 4-3

ii. Gaining Ratio = New Ratio − Old Ratio

Aparna Gaining share
Chp 4-4

Chp 4-5

Gaining Ratio between Aparna and Sonia = 3: 7

iii. Aparna’s share in the goodwill
Chp 4-6

Sonia’s share in the goodwill
f

Q2Written answer

Sangeeta, Saroj and Shanti are partners sharing profits in the ratio of 2:3:5. Goodwill is appearing in the books at a value of ₹ 60,000. Sangeeta retires, and goodwill is valued at ₹ 90,000. Saroj and Shanti decided to share future profits equally. Record necessary Journal entries.


Show solutionHide solution
Worked solution
 Books of Saroj and Shanti


Journal


Date Particulars L.F. Amount

₹

Amount

₹

Sangeeta’s Capital A/c Dr. 12,000
Saroj’s Capital A/c Dr. 18,000
Shanti’s Capital A/c Dr. 30,000
To Goodwill A/c 60,000
(Goodwill written off)
Saroj’s Capital A/c Dr. 18,000
To Sangeeta’s Capital A/c 18,000
(Sangeeta’s share of goodwill adjusted to Saroj’s Capital

Account in her gaining ratio)

Working Notes:

i. Sangeeta’s share of goodwill

Total goodwill of the firm × Retiring partner’s share Chp 4-8

ii. Gaining Ratio = New Ratio – Old Ratio

Saroj’s Gaining Share Chp 4-9

Shanti’s Gaining Share Chp 4-10

Q3Written answer

Himanshu, Gagan and Naman are partners sharing profits and losses in the ratio of 3:2:1. On March 31, 2017, Naman retires.

The various liabilities and assets of the firm on the date were as follows:

Cash ₹ 10,000, Building ₹ 1,00,000, Plant and Machinery ₹ 40,000, Stock ₹ 20,000, Debtors ₹ 20,000 and Investments ₹ 30,000.

The following was agreed upon between the partners on Naman’s retirement:

(i) Building to be appreciated by 20%.
(ii) Plant and Machinery are to be depreciated by 10%.
(iii) A provision of 5% on debtors is to be created for bad and doubtful debts.
(iv) The stock is to be valued at ₹ 18,000 and the investment at ₹ 35,000.

Record the necessary journal entries to the above effect and prepare the Revaluation Account.


Show solutionHide solution
Worked solution
 Books of Himanshu and Gagan


Journal

Date Particulars L.F. Amount

₹

Amount

₹

Building A/c Dr. 20,000
Investment A/c Dr. 5,000
To Revaluation A/c Dr. 25,000
(Value of Building and Investment increased at the time

of Naman’s retirement)

Revaluation A/c Dr. 7,000
To Plant and Machinery A/c 4,000
To Provision for Bad and Doubt Debts A/c 1,000
To Stock A/c 2,000
(Assets revalued and provision for Bad and Doubtful Debts

made at the time of Naman’s retirement)

Revaluation A/c Dr. 18,000
To Himanshu’s Capital A/c 9,000
To Gagan’s Capital A/c 6,000
To Naman’s Capital A/c 3,000
(Profit on revaluation transferred to all Partners’ Capital

Accounts in their old profit-sharing ratio)

Revaluation Account
Dr.   Cr.
Particular Amount

₹

Particular Amount

₹

Plant and Machinery 4,000 Building 20,000
Stock 2,000 Investment 5,000
Provision for Bad and Doubtful Debts 1,000
Profit Transferred to Capital Account:
Himanshu 9,000
Gagan 6,000
Naman 3,000 18,000
25,000 25,000
Q4Written answer

Naresh, Raj Kumar and Bishwajeet are equal partners. Raj Kumar decides to retire. On the date of his retirement, the Balance Sheet of the firm showed the following:

General Reserve – ₹ 36,000

Profit and Loss Account (Dr.) – ₹ 15,000.

Pass the necessary journal entries to the above effect.


 Books of Naresh and Bishwajeet

Journal

Date Particulars L.F. Amount

₹

Amount

₹

General Reserve A/c Dr. 36,000
To Naresh’s Capital A/c 12,000
To Raj Kumar’s Capital A/c 12,000
To Bishwajeet’s Capital A/c 12,000
(General Reserve distributed among old partners in old ratio)
Naresh’s Capital A/c Dr. 5,000
Raj Kumar’s Capital A/c Dr. 5,000
Bishwajeet’s Capital A/c Dr. 5,000
To Profit and Loss A/c 15,000
(Debit balance of Profit and Loss Account written off)
Show solutionHide solution
Worked solution

Solution coming soon.

Q5Written answer

Digvijay, Brijesh and Parakaram were partners in a firm, sharing profits in the ratio of 2:2:1. Their Balance Sheet as on March 31, 2017, was as follows:

Liabilities Amount

₹

Assets Amount

₹

Creditors 49,000 Cash 8,000
Reserves 18,500 Debtors 19,000
Digvijay’s Capital 82,000 Stock 42,000
Brijesh’s Capital 60,000 Buildings 2,07,000
Parakaram’s Capital 75,500 Patents 9,000
  2,85,000 2,85,000
       

Brijesh retired on March 31, 2017, on the following terms:

(i)    Goodwill of the firm was valued at ₹ 70,000 and was not to appear in the books.

(ii)   Bad debts amounting to ₹ 2,000 were to be written off.

(iii)  Patents were considered valueless.

Prepare the Revaluation Account, Partners’ Capital Accounts and the Balance Sheet of Digvijay and Parakaram after Brijesh’s retirement.


Show solutionHide solution
Worked solution
 Books of Digvijay and Parakaram

Revaluation Account

Dr.   Cr.
Particular Amount

₹

Particular Amount

₹

Bad Debts 2,000
Patents 9,000 Loss Transferred to Capital Account:
Digvijay 4,400
Brijesh 4,400
Parakaram 2,200
11,000 11,000
Partners’ Capital Account
Dr.   Cr.
Particulars Digvijay Brijesh Parakaram Particulars Digvijay Brijesh Parakaram
Brijesh’s Capital A/c 18,667 9,333 Balance b/d 82,000 60,000 75,500
Revaluation (Loss) 4,400 4,400 2,200 Digvijay’s Capital A/c 18,667
Brijesh’s Loan 91,000 Parakaram’s Capital A/c 9,333
Balance c/d 66,333 67,667 Reserves 7,400 7,400 3,700
89,400 95,400 79,200 89,400 95,400 79,200
Balance Sheet as on March 31, 2017 
Liabilities Amount

₹

Assets Amount

₹

Creditors 49,000 Cash 8,000
Brijesh’s Loan 91,000 Debtors 19,000
Less: Bad Debts 2,000 17,000
Digvijay’s Capital A/c 66,333 Stock 42,000
Parakaram’s Capital A/c 67,667 Buildings 2,07,000
2,74,000 2,74,000

Note: As the sufficient balance is not available to pay the amount due to Brijesh, the balance of his Capital Account is transferred to his Loan Account.

Working Note:

1. Brijesh’s Share of Goodwill

Total goodwill of the firm × Retiring partner’s share Chp 4-11

2. Gaining Ratio = New Ratio – Old Ratio

Digvijay’s ShareChp 4-12

Parakaram’s ShareChp 4-13

Gaining ratio between Digvijay and Parakaram = 4:2 or 2:1


Q6Written answer

Radha, Sheela and Meena were in partnership, sharing profits and losses in the proportion of 3:2:1. On April 1, 2017, Sheela retired from the firm. On that date, their Balance Sheet was as follows:

Liabilities Amount

₹

Assets Amount

₹

Trade Creditors 3,000 Cash-in-Hand 1,500
Bills Payable 4,500 Cash at Bank 7,500
Expenses Owing 4,500 Debtors 15,000
General Reserve 13,500 Stock 12,000
Capitals: Factory Premises 22,500
Radha 15,000 Machinery 8,000
Sheela 15,000 Loose Tools 4,000
Meena 15,000 45,000
    70,500 70,500
         

The terms were:

a) Goodwill of the firm was valued at ₹ 13,500.

b) Expenses owing to be brought down to ₹ 3,750.

c) Machinery and Loose Tools are to be valued at 10% less than their book value.

d) Factory premises are to be revalued at ₹ 24,300.

Prepare:

i. Revaluation account

ii. Partner’s capital accounts 

iii. Balance sheet of the firm after the retirement of Sheela.


Show solutionHide solution
Worked solution
Books of Radha and Meena

Revaluation Account

Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Machinery 800 Expenses Owing 750
Loose Tools 400 Factory Premises 1,800
Profit transferred to Capital Account:
Meena 675
Radha 450
Sheela 225 1,350
2,550 2,550
Parters’ Capital Account
Dr. Cr.
Particulars Radha Sheela Meena Particulars Radha Sheela Meena
Sheela’s Capital A/c 3,375 1,125 Balance b/d 15,000 15,000 15,000
Sheela’s Loan A/c 24,450 General Reserve 6,750 4,500 2,250
Balance c/d 19,050 16,350 Revaluation (Profit) 675 450 225
Radha’s Capital A/c 3,375
Meena’s Capital A/c 1,125
22,425 24,450 17,475 22,425 24,450 17,475
Balance Sheet as on April 01, 2017
Liabilities Amount

₹

Assets Amount

₹

Trade Creditors 3,000 Cash in Hand 1,500
Bills Payable 4,500 Cash at Bank 7,500
Expenses Owing 3,750 Debtors 15,000
Sheela’s Loan 24,450 Stock 12,000
Factory Premises 24,300
Capitals: Machinery 8,000
Radha 19,050 Less: 10% (800) 7,200
Meena 16,350 35,400 Loose Tools 4,000
Less: 10% (400) 3,600
71,100 71,100
         

Working Notes:

Working Notes:

1) Sheela’s share of goodwill

Total goodwill of the firm × Retiring partner’s share =13,500 × 2/6 = 4,500

2) Gaining Ratio = New Ratio − Old Ratio

Radha’s Share
Chp 4-14

Meena’s Shares
Chp 4-15

Gaining Ratio between Radha and Meena = 6:2 or 3:1


Q7Written answer

Pankaj, Naresh and Saurabh are partners sharing profits in the ratio of 3:2:1. Naresh retired from the firm due to his illness. On that date, the Balance Sheet of the firm was as follows:

Books of Pankaj, Naresh and Saurabh
Balance Sheet as on March 31, 2017
Liabilities Amount ₹ Assets Amount ₹
General Reserve 12,000 Bank 7,600
Sundry Creditors 15,000 Debtors 6,000
Bills Payable 12,000 Less: Provision for Doubtful Debt 400 5,600
Outstanding Salary 2,200
Provision for Legal Damages 6,000 Stock 9,000
Capitals: Furniture 41,000
Pankaj 46,000 Premises 80,000
Naresh 30,000
Saurabh 20,000 96,000
1,43,200 1,43,200

Additional Information

(i) Premises have appreciated by 20%, stock depreciated by 10% and provision for doubtful debts was to be made 5% on debtors. Further, provision for legal damages is to be made for ₹ 1,200 and furniture to be brought up to ₹ 45,000.

(ii) Goodwill of the firm is valued at ₹ 42,000.

(iii) ₹ 26,000 from Naresh’s Capital account be transferred to his loan account, and the balance is paid through the bank; if required, the necessary loan may be obtained from the bank.

(iv) New profit-sharing ratio of Pankaj and Saurabh is decided to be 5:1.

Give the necessary ledger accounts and balance sheet of the firm after Naresh’s retirement.

Show solutionHide solution
Worked solution
Revaluation Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Stock 900 Premises 16,000
Provision for Legal Damages 1,200 Provision for Doubtful Debts 100
Profit Transferred to Capital: Furniture 4,000
Pankaj 9,000
Naresh 6,000
Saurabh 3,000 18,000
20,100 20,100
Partners’ Capital Accounts
Dr. Cr.
Particulars Pankaj Naresh Saurabh Particulars Pankaj Naresh Saurabh
Naresh’s Capital A/c 14,000 Balance b/d 46,000 30,000 20,000
Naresh’s Loan A/c 26,000 General Reserve 6,000 4,000 2,000
Bank 28,000 Revaluation (Profit) 9,000 6,000 3,000
Balance c/d 47,000 25,000 Pankaj’s Capital A/c 14,000
61,000 54,000 25,000 61,000 54,000 25,000
Bank Account
Cr.
Particulars Amount

₹

Particulars Amount

₹

Balance b/d 7,600 Naresh’s Capital A/c 28,000
Bank Loan (Balancing Figure) 20,400
28,000 28,000
Balance Sheet as on March 31, 2017
Liabilities Amount

₹

Assets Amount

₹

Sundry Creditors 15,000 Debtors 6,000
Bills Payable 12,000 Less: Provision for Doubtful Debts 300 5,700
Bank Loan/overdraft 20,400 Stock 8,100
Outstanding Salaries 2,200 Furniture 45,000
Provision for Legal Damages 7,200 Premises 96,000
Naresh’s Loan 26,000
Capitals:
Pankaj 47,000
Saurabh 25,000 72,000
1,54,800 1,54,800
Q8Written answer

Puneet, Pankaj and Pammy are partners in a business, sharing profits and losses in the ratio of 2:2:1, respectively. Their balance sheet as on March 31, 2017, was as follows:

Books of Puneet, Pankaj and Pammy
Balance Sheet as on March 31, 2017
Liabilities Amount

₹

Assets Amount

₹

Sundry Creditors 1,00,000 Cash at Bank 20,000
Capital Accounts: Stock 30,000
Puneet 60,000 Sundry Debtors 80,000
Pankaj 1,00,000 Investments 70,000
Pammy 40,000 2,00,000 Furniture 35,000
Reserve 50,000 Buildings 1,15,000
3,50,000 3,50,000

Mr Pammy died on September 30, 2017. The partnership deed provided the following:

(i) The deceased partner will be entitled to his share of profit up to the date of death calculated on the basis of the previous year’s profit.
(ii) He will be entitled to his share of goodwill of the firm calculated on the basis of 3 years’ purchase of an average of the last 4 years’ profit. The profits for the last four financial years are given below: for 2013–14, ₹ 80,000; for 2014–15, ₹ 50,000; for 2015–16, ₹ 40,000; for 2016–17, ₹ 30,000.

The drawings of the deceased partner up to the date of death amounted to ₹ 10,000. Interest on capital is to be allowed at 12% per annum.

Surviving partners agreed that ₹ 15,400 should be paid to the executors immediately and the balance in four equal yearly instalments with interest at 12% p.a. on the outstanding balance.

Show Mr Pammy’s Capital account, and his Executor’s account, till the settlement of the amount due.

Show solutionHide solution
Worked solution
Pammy’s Capital Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Drawings 10,000 Balance b/d 40,000
Pammy Executor’s A/c 75,400 Profit and Loss (Suspense) 3,000
Puneet’s Capital A/c 15,000
Pankaj’s Capital A/c 15,000
Interest on Capital 2,400
Reserve 10,000
85,400 85,400
Pammy’s Executor Account
Dr. Cr.
Date Particulars J.F. Amount

₹

Date Particulars J.F. Amount

₹

2017-18 2017-18
Sep. 30 Bank 15,400 Sep. 30 Pammy’s Capital A/c 75,400
Mar. 31 Balance c/d 63,600 Mar. 31 Interest 3,600
79,000 79,000
2018-19 2018-19
Sep. 30 Bank 22,200 April 01 Balance b/d 63,600
(15,000+3,600+3,600) Sep. 30 Interest 3,600
Mar. 31 Balance c/d 47,700 Mar. 31 Interest 2,700
69,900 69,900
2019-20 2019-20
Sep. 30 Bank 20,400 April 01 Balance b/d 47,700
Mar. 31 Balance c/d 31,800 Sep. 30 Interest 2,700
Mar. 31 Interest 1,800
52,200 52,200
2020-21 2020-21
Sep. 30 Bank 18,600 April 01 Balance b/d 31,800
(15,000+1,800+1,800) Sep. 30 Interest 1,800
Mar. 31 Balance c/d 15,900 Mar. 31 Interest 900
34,500 34,500
2021-22 2021-22
Sep. 30 Bank 16,800 April 01 Balance b/d 15,900
(15,000+900+900) Sep. 30 Interest 900
16,800 16,800

Working Notes:

1) Pammy’s Share of Profit

Previous Year’s Profit × Proportionate Period × Share of Deceased Partner Chp 4-17
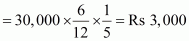
2) Pammy’s Share of Goodwill

Goodwill of the firm = Average Profit × Numbers of Year’s Purchase

Average Profit Chp 4-18
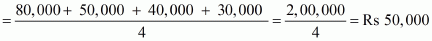
Goodwill of the Firm = 50,000 ´ 3 = ₹ 1,50,000
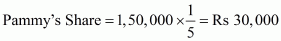
Chp 4-19

3) Gaining Ratio = New Ratio – Old Ratio

Puneet’s ShareChp 4-20
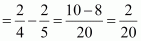
Pankaj’s ShareChp 4-21

Gaining Ratio between Puneet and Pankaj = 2:2 or 1:1

4) Interest on Capital for 6 months, i.e. from April 1, 2007, to September 30, 2007

Amount of Capital × Rate of Interest × Period Chp 4-22
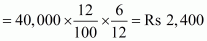
5) Interest Amount

The firm closes its books every year on March 31, while instalments to Pammy’s Executor are paid on September 30 every year.

Amount outstanding on 30 September = 75,400 – 15,400 = ₹ 60,000
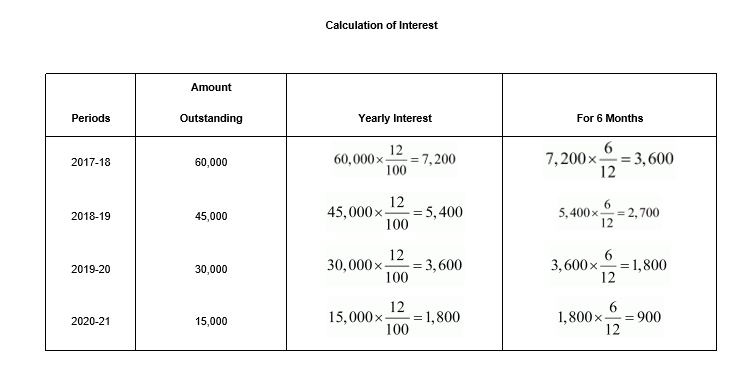
Chp 4-23

Q9Written answer

Following is the Balance Sheet of Prateek, Rockey and Kushal as on March 31, 2017.

Books of Prateek, Rockey and Kushal
Balance Sheet as on March 31, 2017
Liabilities Amount

₹

Assets Amount

₹

Sundry Creditors 16,000 Bills Receivable 16,000
General Reserve 16,000 Furniture 22,600
Capital Accounts: Stock 20,400
Prateek 30,000 Sundry Debtors 22,000
Rockey 20,000 Cash at Bank 18,000
Kushal 20,000 70,000 Cash in Hand 3,000
  1,02,000 1,02,000
       

Rockey died on June 30, 2017. Under the terms of the partnership deed, the executors of a deceased partner were entitled to:

a) Amount standing to the credit of the Partner’s Capital account.

b) Interest on capital at 5% per annum.

c) Share of goodwill on the basis of twice the average of the past three years’ profit.

d) Share of profit from the closing date of the last financial year to the date of death on the basis of last year’s profit.

Profits for the year ending on March 31, 2015, March 31, 2016, and March 31, 2017, were ₹ 12,000, ₹ 16,000 and ₹ 14,000, respectively. Profits were shared in the ratio of capital.

Pass the necessary journal entries and draw up Rockey’s capital account to be rendered to his executor.

Show solutionHide solution
Worked solution
 Books of Prateek and Kushal

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2017
June 30 Interest on Capital A/c Dr. 250
Profit and Loss (Suspense) A/c Dr. 1,000
General Reserve A/c Dr. 4,571
To Rockey’s Capital A/c 5,821
(Share of profit, interest on capital and share of General

Reserve credited to Rockey’s Capital Account)

June 30 Prateek’s Capital A/c Dr. 4,800
Kushal’s Capital A/c Dr. 3,200
To Rockey’s Capital A/c 8,000
(Rockey’s share of goodwill adjusted to Prateek’s and

Kushal’s Capital Account in their gaining ratio, 3:2)

June 30 Rockey’s Capital A/c Dr. 33,821
To Rockey Executor’s A/c 33,821
(Balance of Rockey’s Capital Account transferred to his

Executor’s Account)

Rockey’s Capital Account
Dr. Cr.
Date Particulars J.F. Amount

₹

Date Particulars J.F. Amount

₹

2017 2017
April 1 Rockey’s Executor A/c 33,821 April 1 Balance b/d 20,000
Interest on Capital 250
Profit and Loss (Suspense) A/c 1,000
General Reserve 4,571
Prateek’s Capital 4,800
Kushal’s Capital 3,200
33,821 33,821

Working Notes:

1. Rockey’s Share of Profit = Previous Year’s Profit × Proportionate Period × Share of Deceased Partner

=
Chp 4-24

2. Rockey’s Share of Goodwill

Goodwill of a firm = Average profit × Numbers of Year’s Purchase

Chp 4-25

Goodwill of a firm = 14,000 × 2 = ₹ 28,000

Chp 4-26

3. Gaining Ratio = New Ratio − Old Ratio

Chp 4-27

Chp 4-28

Gaining Ratio between Prateek and Kushal = 9:4 or 3:2

4. Interest on Capital for 3 months, i.e. from April 1, 2017, to June 30, 2017

Amount of × Rate of Interest × Period
Chp 4-29


Q10Written answer

Narang, Suri and Bajaj are partners in a firm, sharing profits and losses in the proportion of 1/2, 1/6 and 1/3, respectively. The Balance Sheet on April 1, 2015, was as follows:

Books of Suri, Narang and Bajaj

Balance Sheet as on April 1, 2015

Liabilities Amount

₹

Assets Amount

₹

Bills Payable 12,000 Freehold Premises 40,000
Sundry Creditors 18,000 Machinery 30,000
Reserves 12,000 Furniture 12,000
Capital Accounts: Stock 22,000
Narang 30,000 Sundry Debtors 20,000
Suri 20,000 Less: Reserve 1,000 19,000
Bajaj 28,000 88,000 for Bad Debt
Cash 7,000
  1,30,000 1,30,000
       

Bajaj retires from the business, and the partners agree to the following:

a) Freehold premises and stock are to be appreciated by 20% and 15%, respectively.

b) Machinery and furniture are to be depreciated by 10% and 7%, respectively.

c) Bad Debts reserve is to be increased to ₹ 1,500.

d) Goodwill is valued at ₹ 21,000 on Bajaj’s retirement.

e) The continuing partners have decided to adjust their capital in their new profit-sharing ratio after the retirement of Bajaj. Surplus/deficit, if any, in their capital accounts will be adjusted through current accounts.

Prepare necessary ledger accounts and draw the Balance Sheet of the reconstituted firm.


Show solutionHide solution
Worked solution
Revaluation Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Machinery 3,000 Freehold Properties 8,000
Furniture 840 Stock 3,300
Reserve for Bad debts 500
Capitals:
Narang 3,480
Suri 1,160
Bajaj 2,320 6,960
11,300 11,300
Partners’ Capital Account
Dr. Cr.
Particulars Narang Suri Bajaj Particulars Narang Suri Bajaj
Bajaj’s Capital A/c 5,250 1,750 Balance b/d 30,000 30,000 28,000
Bajaj’s Loan 41,320 Reserves 6,000 2,000 4,000
Revaluation (Profit) 3,480 1,160 2,320
Balance c/d 34,230 31,410 Narang’s Capital A/c 5,250
Suri’s Capital A/c 1,750
39,480 33,160 41,320 39,480 33,160 41,320
Suri’s Current A/c 15,000 Balance b/d 34,230 31,410
Narang’s Current A/c 15,000
Balance c/d 49,230 16,410
49,230 31,410 49,230 31,410
Balance Sheet as on April 01, 2015
Liabilities Amount

₹

Assets Amount

₹

Bills Payable 12,000 Freehold Premises 48,000
Sundry Creditors 18,000 Machinery 27,000
Bajaj’s Loan 41,320 Furniture 11,160
Suri’s Current 15,000 Stock 25,300
Capital Account: Sundry Debtors 20,000
Narang 49,230 Less: Reserve for Bad Debt 1,500 18,500
Suri 16,410 65,640 Cash 7,000
Narang’s Current Account 15,000
1,51,960 1,51,960

Working Notes:

1. Bajaj Share in Goodwill = Total Goodwill of the firm x Retiring partner’s share = Chp 4-30

2. Gaining Ratio = New Ratio – Old Ratio

Chp 4-31

Chp 4-32

Gaining Ratio between Narang and Suri = 3:1

3. Calculation of New Capitals of the existing partners.

Balance in Narang’s Capital = 34,230
Balance in Suri’s Capital = 31,410
Total Capital of the New firm after revaluation of assets and
liabilities and adjustment of  Goodwill and Reserves = ₹ 65,640

Based on the new profit-sharing ratio of 3:1

Chp 4-33

Chp 4-34

NOTE:

i. In the given question, Suri’s Capital is ₹ 30,000 instead of ₹ 20,000.

ii. Due to an insufficient balance in Bajaj’s Capital Account, the amount due to Bajaj is transferred to his Loan Account.