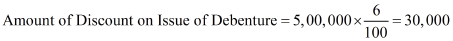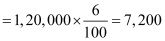My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 2: Issue and Redemption of Debentures

Practice each question, then open the answer or worked solution.

Numerical Questions for NCERT Accountancy Solutions Part 2 Class 12 Chapter 2

20 questions
Q11Written answer

X.Ltd. purchased a Machinery from Y for an agreed purchase consideration of ₹ 4, 40,000 to be satisfied by the issue of 12% debentures of ₹ 100 each at a premium of ₹ 10 per debenture. Journalise the transactions.

Show solutionHide solution
Worked solution

The solution to this question is as follows

Books of X. Ltd.


Journal


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Machinery A/c Dr. 4,40,000
To Y 4,40,000
(Machinery purchased from Y)
Y Dr. 4,40,000
To 12% Debentures A/c 4,00,000
To Securities Premium A/c 40,000
(Allotted 4,000 debentures of ₹ 100 each at a premium

of ₹ 10 per debenture in consideration of Machinery

purchased)

Q12Written answer

X.Ltd. issued 15,000, 10% debentures of ₹ 100 each. Give journal entries and the Balance Sheet in each of the following cases:

(i) The debentures are issued at a premium of 10%;

(ii) The debentures are issued at a discount of 5%;

(iii) The debentures are issued as a collateral security to bank against a loan of ₹ 12, 00,000; and

(iv) The debentures are issued to a supplier of machinery costing ₹ 13, 50,000.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

(i)

Books of X. Ltd.

Journal

Date Particulars L.F. Debit

Amount

₹

Credit

Amount ₹

Bank A/c Dr. 16,50,000
To 10% Debentures A/c 15,00,000
To Securities Premium A/c 1,50,000
(Issued 15,000, 10% debentures of ₹ 100 each at

10% premium)

X Ltd.
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholders’ Funds
 a. Reserves and Surplus 1 1,50,000
2. Non-Current Liabilities
a. Long-Term Borrowings 2 15,00,000
3. Current Liabilities
Total 16,50,000
II. Assets
1. Non-Current Assets
2. Current Assets
a. Cash and Cash Equivalents 3 16,50,000
Total 16,50,000

ACCOUNT NOTES

Note No. Particulars Amount

(₹)

1 Reserves and Surplus
Securities Premium 1,50,000
2 Long-Term Borrowings
10% Debentures (Secured) 15,00,000
3 Cash and Cash Equivalents
Cash at Bank 16,50,000

(ii)

Bank A/c Dr. 14,25,000
Discount on Issue of Debentures A/c Dr. 75,000
To 10% Debentures 15,00,000
(Issued 15,000 10% Debenture of ₹ 100 each at

5% discount)

X Ltd.
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholder’s Funds
2. Non-Current Liabilities
a. Long-Term Borrowings 1 15,00,000
3. Current Liabilities
Total 15,00,000
II. Assets
1. Non-Current Assets
a. Other Non-Current Assets 2 75,000
2. Current Assets
a. Cash and Cash Equivalents 3 14,25,000
Total 15,00,000

ACCOUNT NOTES

Note No. Particulars Amount

(₹)

1 Long-Term Borrowings
10% Debentures (Secured) 15,00,000
2 Other Non-Current Assets
Discount on Issue of Debentures 75,000
3 Cash and Cash Equivalents
Cash at Bank 14,25,000

(iii) No entry will be passed for issuing debentures as a collateral security

X Ltd.
Balance Sheet
Particulars Note

No.

Amount

(₹)

I. Equity and Liabilities
1. Shareholders’ Funds
2. Non-Current Liabilities
a. Long-Term Borrowings 1 12,00,000
3. Current Liabilities
Total 12,00,000
II. Assets
1. Non-Current Assets
2. Current Assets
a. Cash and Cash Equivalents 2 12,00,000
Total 12,00,000

ACCOUNT NOTES

Note No. Particulars Amount

(₹)

1 Long-Term Borrowings
Bank Loan (Secured against issue Debentures of ₹ 12,00,000) 12,00,000
2 Cash and Cash Equivalents
Cash at Bank 12,00,000

Alternative Method

Debenture Suspense A/c Dr. 15,00,000
To 10% Debentures A/c 15,00,000
(Issued 15,000 10% Debentures of ₹ 100 each as collateral security to bank against a loan of ₹ 12,00,000)
X Ltd.
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholders’ Fund
2. Non-Current Liabilities
a. Long-Term Borrowings 1 12,00,000
3. Current Liabilities
Total 12,00,000
II. Assets
1. Non-Current Assets
2. Current Assets
a. Cash and Cash Equivalents 2 12,00,000
Total 12,00,000

ACCOUNT NOTES

Note No. Particulars Amount

(₹)

1 Long Term Borrowings
Secured:
Bank Loan 12,00,000
10 % Debentures (Secured against issue of Debentures of ₹ 12,00,000) 15,00,000
Less: Debenture Suspense Account 15,00,000 –
12,00,000
2 Cash and Cash Equivalents
Cash at Bank 12,00,000

(iv)

Machinery A/c Dr. 13,50,000
To Vendor A/c 13,50,000
(Machinery purchased from vendor)
Vendor A/c Dr. 13,50,000
Discount on Issue of Debentures A/c Dr. 1,50,000
To 10% Debenture A/c 15,00,000
(15,000 10% Debentures @ ₹ 100 each issued at

10% discount to the vendor in consideration of

Machinery of ₹ 13,50,000)

X Ltd.
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholders’ Funds
2. Non-Current Liabilities
a. Long Term Borrowings 1 15,00,000
3. Current Liabilities
Total 15,00,000
II. Assets
1. Non-Current Assets
a. Fixed Assets
i. Tangible Assets 2 13,50,000
b. Other Non-Current Assets 3 1,50,000
2. Current Assets
Total 15,00,000

ACCOUNT NOTES

Note No. Particulars Amount

(₹)

1 Long Term Borrowings
10% Debentures (Secured) 15,00,000
2 Tangible Assets
Plant and Machinery 13,50,000
3 Other Non-Current Assets
Discount on Issue of Debentures 1,50,000
Q13Written answer

Journalise the following:

(i) A debenture issued at ₹ 95, repayable at ₹ 100;

(ii) A debenture issued at ₹ 95, repayable at ₹ 105; and

(iii) A debenture issued at ₹ 100, repayable at ₹ 105;

The face value of debenture in each of the above cases is ₹ 100.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

S.No. Particulars L.F. Debit

Amount

₹

Credit

Amount ₹

(i) Bank A/c Dr. 95
Discount on Issue of Debenture A/c Dr. 5
To Debenture A/c 100
(Debenture of ₹ 100 issued at ₹ 5 discount

with the term repayable at ₹ 100)

(ii) Bank A/c Dr. 95
Loss on Issue of Debenture A/c Dr. 10
To Debenture A/c 100
To Premium on Redemption of Debentures 5
(Debenture of ₹ 100 issued at a discount of

₹ 5 and with the term repayable at ₹ 105)

(iii) Bank A/c Dr. 100
Loss on Issue of Debenture A/c Dr. 5
To Debenture A/c 100
To Premium on Redemption of Debenture A/c 5
(Debenture of ₹ 100 issued with the term

repayable at ₹ 105)

Q14Written answer

A.Ltd. Issued 50, 00,000, 8% Debenture of ₹ 100 at a discount of 6% on April 01, 2009 redeemable at premium of 4% by draw of lots as under:

20, 00,000 Debentures on March, 2011

10, 00,000 Debentures on March, 2013

20, 00,000 Debentures on March, 2014

Compute the amount of discount to be written-off in each year till debentures are paid. Also prepare discount/loss on issue of debenture account.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Loss on issue of debenture = 6% (discount on issue) + 4% (premium on redemption) = 10%

At the end of Debenture Outstanding Ratio Loss to be written off every year
March 2010 50,00,00,000 5 = 1,38,88,889
March 2011 50,00,00,000 5 = 1,38,88,889
March 2012 30,00,00,000 3 = 83,33,333
March 2013 30,00,00,000 3 = 83,33,333
March 2014 20,00,00,000 2 = 55,55,556
18 Rs 5,00,00,000
Loss on Issue of Debenture Account
Dr.             Cr.
Date Particulars J.F. Amount

₹

Date Particulars J.F. Amount

₹

2009

April 01

Debenture 5,00,00,000 2010

March 31

Profit and Loss 1,38,88,889
Balance c/d 3,61,11,111
5,00,00,000 5,00,00,000
2010

April 01

Balance b/d 3,61,11,111 2011

March 31

Profit and Loss 1,38,88,889
Balance c/d 2,22,22,222
3,61,11,111 3,61,11,111
2011

April 01

Balance b/d 2,22,22,222 2012

March 31

Profit and Loss 83,33,333
Balance c/d 1,38,88,889
2,22,22,222 2,22,22,222
2012

April 01

Balance b/d 1,38,88,889 2013

March 31

Profit and Loss 83,33,333
Balance c/d 55,55,556
1,38,88,889 1,38,88,889
2013

April 01

Balance b/d 55,55,556 2014

March 31

Profit and Loss 55,55,556
55,55,556 55,55,556
Q15Written answer

A company issues the following debentures:

(i) 10,000, 12% debentures of ₹ 100 each at par but redeemable at premium of 5% after 5 years;

(ii) 10,000, 12% debentures of ₹ 100 each at a discount of 10% but redeemable at par after 5 years;

(iii) 5,000, 12% debentures of ₹ 1,000 each at a premium of 5% but redeemable at par after 5 years;

(iv) 1,000, 12% debentures of ₹ 100 each issued to a supplier of machinery costing ₹ 95,000. The debentures are repayable after 5 years; and

(v) 300, 12% debentures of ₹ 100 each as a collateral security to a bank which has advanced a loan of ₹ 25,000 to the company for a period of 5 years.

Pass the journal entries to record the: (a) issue of debentures; and (b) repayment of debentures after the given period.

Show solutionHide solution
Worked solution

The solution to this question is as follows


In the books of …………..

Journal

a) Issue of Debentures


S. No.

Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

(i) Bank A/c Dr. 10,00,000
To 12% Debenture Application A/c 10,00,000
(Debenture Application money of 10,000 12% debentures

@ 100 each received)

12% Debenture Application A/c Dr. 10,00,000
Loss on Issue of Debenture A/c Dr. 50,000
To 12% Debenture A/c 10,00,000
To Premium on Redemption of Debenture A/c 50,000
(Debenture Application money of 10,000 12% debentures @ ₹ 100 each transferred to 12% Debentures Account and the Debentures are issued with term of repayable at 5% premium)
(ii) Bank A/c Dr. 9,00,000
To Debenture Application and Allotment A/c 9,00,000
(Debenture Application money received excluding discount on issue)
12% Debenture Application & Allotment A/c Dr. 9,00,000
Discount on Issue of Debenture A/c Dr. 1,00,000
To Debentures A/c 10,00,000
(Debenture Allotment made due)
(iii) Bank A/c Dr. 52,50,000
To Debenture Application and Allotment A/c 52,50,000
(Debenture Application money received)
Debenture Application and Allotment A/c Dr. 52,50,000
To Debenture A/c 50,00,000
To Security Premium A/c 2,50,000
(Allotment of debenture at premium)
(iv) Machinery A/c Dr. 95,000
To Vender A/c 95,000
(Machinery purchased from supplier)
Vender A/c Dr. 95,000
Discount on Issue of Debenture Dr. 5,000
To 12% Debenture A/c 1,00,000
(Debenture issue at discount to vender of machinery)
(v) 12% Debenture Suspense A/c Dr. 30,000
To Debenture A/c 30,000
(300, 12% Debentures of ₹ 100 each issued as collateral

security to the bank against a loan of ₹ 25,000)

b) Repayment of Debentures


S.No.

Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

(i) 12% Debentures A/c Dr. 10,00,000
Premium on Redemption of Debenture A/c Dr. 50,000
To Debenture Holders A/c 10,50,000
(Amount due on redemption of debentures)
Debenture Holders A/c Dr. 10,50,000
To Bank A/c 10,50,000
(Payment made to Debenture Holders)
(ii) 12% Debenture A/c Dr. 10,00,000
To Debenture Holders A/c 10,00,000
(Amount due on redemption of debentures)
Debenture Holders A/c Dr. 10,00,000
To Bank A/c 10,00,000
(Payment made to Debenture Holders)
(iii) 12% Debenture A/c Dr. 50,00,000
To Debenture Holders A/c 50,00,000
(Amount due on redemption of debentures)
Debenture Holders A/c Dr. 50,00,000
To Bank A/c 50,00,000
(Payment made to Debenture Holders)
(iv) 12% Debenture A/c Dr. 1,00,000
To Vender A/c 1,00,000
(Amount due to vender)
Vender A/c Dr. 1,00,000
To Bank 1,00,000
(Payment made to vender)
(v) 12% Debenture A/c Dr. 30,000
To Debenture Suspense A/c 30,000
(Debenture and debenture Suspense Account closed)
Q16Written answer

A company issued debentures of the face value of ₹ 5, 00,000 at a discount of 6% on April 01, 2012. These debentures are redeemable by annual drawings of ₹, 1, 00,000 made on March 31 each year. The directors decided to write off discount based on the debentures outstanding each year.

Calculate the amount of discount to be written-off each year. Give journal entries also.

Show solutionHide solution
Worked solution

The solution to this question is as follows

Journal


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

2012
Apr 1  Bank A/c Dr. 4,70,000
To Debenture Application and Allotment A/c 4,70,000
(Debenture Application money received)
Apr 1 Debenture Application and Allotment A/c Dr. 4,70,000
Discount on Issue of Debenture A/c Dr. 30,000
To Debentures A/c 5,00,000
(Debenture Application money transferred to Debenture Account)

Assuming that the amount of discount on issue of debentures is to be written off in 5 years.

Year Debenture outstanding Ratio Amount written off
2012 5,00,000 5 = 10,000
2013 4,00,000 4 = 8,000
2014 3,00,000 3 = 6,000
2015 2,00,000 2 = 4,000
2016 1,00,000 1 = 2,000
15 30,000
Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

2013

Mar 31

Profit and Loss A/c Dr. 10,000
To Discount on Issue of Debentures A/c 10,000
(Discount on issue of debentures written off)
2014
Mar 31 Profit and Loss A/c Dr. 8,000
To Discount on Issue of Debentures A/c 8,000
(Discount on issue of debentures written off)
2015
Mar 31 Profit and Loss A/c Dr. 6,000
To Discount on Issue of Debenture A/c 6,000
(Discount on issue of debentures written off)
2016
Mar 31 Profit and Loss A/c Dr. 4,000
To Discount on issue of Debentures A/c 4,000
(Discount on issue of debenture written off)
2017
Mar 31 Profit and Loss A/c Dr. 2,000
To Discount on Issue of Debenture A/c 2,000
(Discount on issue of debenture written off)
Q17Written answer

A company issued 10% Debentures of the face value of ₹, 1, 20,000 at a discount of 6% on April 01, 2011. The debentures are payable by annual drawings of ₹ 40,000 commencing from the end of third year.

How will you deal with discount on debentures?

Show the discount on debentures account in the company ledger for the period of duration of debentures. Assume accounts are closed on March 31 every year.

Show solutionHide solution
Worked solution

The solution to this question is as follows

In the books of……………

Journal

Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

2011

Apr. 01

Bank A/c Dr. 1,12,800
To Debenture Application and Allotment A/c 1,12,800
(Debentures Application Money received)
Apr. 01 Debentures Application and Allotment A/c Dr. 1,12,800
Discount on issue of Debenture A/c Dr. 7,200
To 10% Debenture A/c 1,20,000
(Debenture Application Money transferred to Debenture Account)
2012

Mar. 31

Profit and Loss A/c Dr. 1,800
To Discount on Issue of Debentures A/c 1,800
(Discount on issue of debenture written off)
2013

Mar. 31

Profit and Loss A/c Dr. 1,800
To Discount on Issue of Debenture A/c 1,800
(Discount on issue of debenture written off)
2014

Mar. 31

Profit and Loss A/c Dr. 1,800
To Discount on Issue of Debenture A/c 1,800
(Discount on issue of debenture written off)
2015
Mar. 31 Profit and Loss A/c Dr. 1,200
To Discount on Issue of Debentures A/c 1,200
(Discount on issue of debenture written off)
2016
Mar. 31 Profit and Loss A/c Dr. 600
To Discount on Issue of Debentures A/c 600
(Discount on issue of debenture written off)
Discount on Issue of Debentures
Dr. Cr.
Date Particulars J.F. Amount

₹

Date Particulars J.F. Amount

₹

2011

Apr. 01

10% Debentures 7,200 2012

Mar. 31

Profit and Loss 1,800
Balance c/d 5,400
7,200 7,200
2012

Apr. 01

Balance b/d 5,400 2013

Mar. 31

Profit and Loss 1,800
Balance c/d 3,600
5,400 5,400
2013

Apr. 01

Balance b/d 3,600 2014

Mar. 31

Profit and Loss 1,800
Balance c/d 1,800
3,600 3,600
2014

Apr. 01

Balance b/d 1,800 2015

Mar. 31

Profit and Loss 1,200
Balance c/d 600
1,800 1,800
2015

Apr. 01

Balance b/d 600 2016

Mar 31

Profit and Loss 600
600 600

i) Working Note:

Amount of Discount on Issue of Debenture:
12-12

Year Debenture Outstanding Ratio Amount written off every year
2011-12 1,20,000 3 = 1,800
2012-13 1,20,000 3 = 1,800
2013-14 1,20,000 3 = 1,800
2014-15 80,000 2 = 1,200
2015-16 40,000 1 = 600
12  ₹ 7,200
Q18Written answer

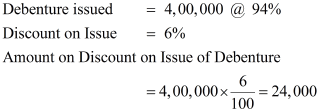
B. Ltd. issued debentures at 94% for ₹ 4, 00,000 on April 01, 2011 repayable by five equal drawings of ₹ 80,000 each. The company prepares its final accounts on March 31 every year.

Indicate the amount of discount to be written-off every accounting year assuming that the company decides to write-off the debentures discount during the life of debentures. (Amount to be written-off: 2012 ₹ 8,000; 2013 ₹ 6,400; 2014 ₹ 4,800; 2015 ₹ 2,000; 2016 ₹ 1,600).

Show solutionHide solution
Worked solution

The solution to this question is as follows:

12-13

Amount of discount to written off every year

In 2012 = ₹8,000

In 2013 = ₹6,400

In 2014 = ₹4,800

In 2015 = ₹3,200

In 2016 = ₹1,600

​

Working Notes:

Year Debentures Outstanding Ratio Months New Ratio (Ratio × Months) Amounts written off
2012
Apr-Mar 3,20,000 5 12 60 24,000×60180=₹8,00024,000×60180=₹8,000
2013
Apr-Mar 2,40,000 4 12 48 24,000×48180=₹6,40024,000×48180=₹6,400
2014
Apr-Mar 1,60,000 3 12 36 24,000×36180=₹4,80024,000×36180=₹4,800
2015
Apr-Mar 80,000 2 12 24 24,000×24180=₹3,20024,000×24180=₹3,200
2016
Apr-Mar 80,000 1 12 12 24,000×12180=₹1,60024,000×12180=₹1,600
180

Important Note: As per NCERT textbook, ₹2,000 discount has been written off in the year 2015 which is incorrect because then the total discount amounts to ₹22,800. Therefore, it should be ₹3,200. 


Q19Written answer

B. Ltd. issued 1,000, 12% debentures of ₹ 100 each on April 01, 2014 at a discount of 5% redeemable at a premium of 10%.

Give journal entries relating to the issue of debentures and debentures interest for the period ending March 31, 2015 assuming that interest is paid half yearly on September 30 and March 31 and tax deducted at source is 10%.

Show solutionHide solution
Worked solution

The solution to this question is as follows

Date Particulars L.F. Debit

Amount

₹

Credit

Amount ₹

2014
Apr. 01 Bank A/c Dr. 95,000
Loss on Issue on Debentures A/c Dr. 15,000
To 12% Debenture A/c 1,00,000
To Premium on Redemption of Debentures A/c 10,000
(Debenture issued at discount and redeemable at Premium)
Sept. 30 Debenture Interest A/c Dr. 6,000
To Income Tax Payable A/c 600
To Debenture Holders A/c 5,400
(Amount of interest on 12% debentures ₹ 1,00,000 due for

6 months and 10% tax deducted at source)

Sept. 30 Debenture Holders A/c Dr. 5,400
To Bank A/c 5,400
(Interest paid to Debenture Holders)
2015

Mar. 31

Debenture Interest A/c Dr. 6,000
To Income Tax Payable A/c 600
To Debenture Holders A/c 5,400
(Amount of interest on 12% Debentures ₹ 1,00,000 due for

6 months and 10% tax deducted at source)

Mar. 31 Debenture Holders A/c Dr. 5,400
To Bank A/c 5,400
(Interest paid to Debenture Holders)
Mar. 31 Profit and Loss A/c Dr. 12,000
To Debenture Interest A/c 12,000
(Interest on debentures transferred to Profit and Loss Account)
Q20Written answer

What journal entries will be made in the following cases when company redeems debentures at the expiry of period by serving the notice: (a) when debentures were issued at par with a condition to redeem them at premium; (b) when debentures were issued at premium with a condition to redeem that at par; and (c) when debentures were issued at discount with a condition to redeem them at premium?

Show solutionHide solution
Worked solution

The solution to this question is as follows:

S.No. Particulars L.F. Debit

Amount

₹

Credit

Amount ₹

(a) Debenture A/c Dr.
Premium on Redemption of Debenture A/c Dr.
To Debenture Holders A/c
(Amount due for  redemption of Debentures)
Debenture Holders A/c Dr.
To Bank A/c
(Payment made to Debenture Holders)
(b) Debenture A/c Dr.
To Debenture Holders A/c
(Amount due for redemption of debentures that were issued at

premium with term of redeemable at par)

Debenture Holders A/c Dr.
To Bank A/c
(Payment made to Debenture Holders)
(c) Debenture A/c Dr.
Premium on Redemption of Debenture A/c Dr.
To Debentures Holders A/c
(Amount due for redemption on debentures that were issued at

discount with the term of redeemable at premium)

Debenture Holders A/c Dr.
To Bank A/c
(Payment made to Debenture Holders)

Concepts covered in this chapter –

  • Meaning and definition of debentures
  • Difference between Shares and Debentures
  • Types of debentures
  • Issue of debentures
  • Over subscription
  • Interest on debentures
  • Sinking fund method
Conclusion