My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 1: Accounting for Share Capital

Practice each question, then open the answer or worked solution.

Numerical Questions for NCERT Accountancy Solutions Part 2 Class 12 Chapter 1

24 questions
Q11Written answer

Naman Ltd issued 20,000 shares of ₹ 100 each, payable ₹ 25 on application, ₹ 30 on allotment, ₹ 25 on first call and the balance on final call. All money duly received except Anubha, who holding 200 shares did not pay allotment and calls money and Kumkum, who holding 100 shares did not pay both the calls. The directors forfeited shares of Anubha and Kumkum.

Give journal entries.

Show solutionHide solution
Worked solution
Books of Naman Ltd


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 5,00,000
To Share Application A/c 5,00,000
(Shares Application money received for 20,000 shares @ ₹ 25 each)
Share Application A/c Dr. 5,00,000
To Share Capital 5,00,000
(Share Application money of 20,000 shares @ ₹ 25 each

transferred to Share Capital Account)

Share Allotment A/c Dr. 6,00,000
To Share Capital A/c 6,00,000
(Share Allotment due on 20,000 shares @ ₹ 30 each)
Bank A/c Dr. 5,94,000
To Share Allotment A/c 5,94,000
(Allotment money received for 19,800 shares @ ₹ 30 per share)
Share First Call A/c Dr. 5,00,000
To Share Capital A/c 5,00,000
(Share First Call money due on 20,000 @ ₹ 25 per share)
Bank A/c Dr. 4,92,500
To Share First Call A/c 4,92,500
(Share First Call received @ ₹ 25 per share for 19,700 shares)
Share Final Call A/c Dr. 4,00,000
To Share Capital A/c 4,00,000
(Share Final Call money due on 20,000 shares @ 20 per share)
Bank A/c Dr. 3,94,000
To Share final call A/c 3,94,000
(Share Final Call received @ ₹ 20 per Share  for 19,700

shares and 300 shares failed to pay the call)

Share Capital A/c Dr. 30,000
To Share Forfeiture A/c (200×25+100×55) 10,500
To Share Allotment (200×30) 6,000
To Share First Call A/c (300×25) 7,500
To Share Final Call A/c (300×20) 6,000
(300 Shares forfeited)

It can also be solved by debiting Calls in Arrears Account

Books of Naman Ltd


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 5,00,000
To Share Application A/c 5,00,000
(Share Application money received on application for 20,000 shares @ ₹ 25 per share)
Share Application A/c Dr. 5,00,000
To Share Capital A/c 5,00,000
(Share Application money for 20,000 shares @ ₹ 25 per share

transferred to Share Capital Account)

Share Allotment A/c Dr. 6,00,000
To Share Capital A/c 6,00,000
(Share Allotment money due on 20,000 shares @ ₹ 30 per share)
Bank A/c Dr. 5,94,000
Calls in Arrears A/c Dr. 6,000
To Share Allotment A/c 6,00,000
(Allotment money received for 19,800 shares @ ₹ 30 per

share and 200 shares failed to pay the Allotment)

Share First Call A/c Dr. 5,00,000
To Share Capital A/c 5,00,000
(Share First Call money due on 20,000 shares @ ₹ 25 per share)
Bank A/c Dr. 4,92,500
Calls in Arrears A/c Dr. 7,500
To Share First Call A/c 5,00,000
(Share First Call money for 19,700 shares @ ₹ 25

each received except 300 shares)

Share Final Call A/c Dr. 4,00,000
To Share Capital A/c 4,00,000
(Share Final Call money due on 20,000 shares @ ₹ 20 per share)
Bank A/c Dr. 3,94,000
Calls in Arreras A/c Dr. 6,000
To Share final call A/c 4,00,000
(Share Final Call money received for 19,700 shares @ ₹ 20 per share

except 300 shares)

Share Capital A/c Dr. 30,000
To Share Forfeiture A/c (200×25+100×55) 10,500
To Calls in Arrears A/c 19,500
(300 Shares forfeited on account failed to pay the money due)

Working Note:


1. Forfeited Amount

Amount on application (300 shares @ ₹ 25 each) = 7,500
Amount on allotment (100 Shares @ ₹ 30 each) = 3,000
10,500
Q12Written answer

Kishna Ltd issued 15,000 shares of ₹ 100 each at a premium of ₹ 10 per share, payable as follows:


On application ₹ 30
On allotment ₹ 50 (including premium)
On first and final call ₹ 30


All the shares subscribed and the company received all the money due, With the exception of the allotment and call money on 150 shares. These shares were forfeited and reissued to Neha as fully paid share of ₹ 12 each.


Give journal entries in the books of the company.

Show solutionHide solution
Worked solution
Books of Krishna Ltd


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 4,50,000
To Share Application A/c 4,50,000
(Share Application money received for 15,000 shares @ ₹ 30 per share)
Share Application A/c Dr. 4,50,000
To Share Capital A/c 4,50,000
(Share Application money of 15,000 shares transferred to Share

Capital Account)

Share Allotment A/c Dr. 7,50,000
To Share Capital A/c 6,00,000
To Securities Premium A/c 1,50,000
(Share Allotment money on 15,000 shares @ ₹ 50 per share

including ₹ 10 securities premium due)

Bank A/c Dr. 7,42,500
To Share Allotment A/c 7,42,500
(Share Allotment received on 14,850 shares and 150 shares

failed to pay the money due)

Share First and Final Call A/c Dr. 4,50,000
To Share Capital A/c 4,50,000
(Share First and Final Call for 15,000 shares @ ₹ 30 per share due)
Bank A/c Dr. 4,45,500
To Share First and Final Call A/c 4,45,500
(Share First and Final Call received for 14,850 shares @ ₹ 30 per share and 150 shares failed to pay amount due)
Share Capital A/c (150×100) Dr. 15,000
Share Premium A/c (150×10) Dr. 1,500
To Share Allotment A/c (150×50) 7,500
To Share First and Final Call A/c (150×30) 4,500
To Share Forfeiture A/c (150×30) 4,500
(150 shares forfeited for non-payment of Share Allotment and Share

First and Final Call  )

Bank A/c Dr. 18,000
To  Share Capital A/c 15,000
To Securities Premium A/c 3,000
(150 shares of ₹ 100 each reissued @ ₹ 120 to Neha)
Share Forfeiture A/c Dr. 4,500
To Capital Reserve A/c 4,500
(Balance of Share Forfeiture Account transferred to Capital Reserve

Account)

Note: In the solution, the reissued price of ₹ 12 has been assumed as ₹ 120 per share.

Q13Written answer

Arushi Computers Ltd. issued 10,000 equity shares of ₹. 100 each at 10% premium. The net amount payable as follows:


On application ₹. 20
On allotment ₹. 50 (₹. 40 + premium ₹. 10)
On first call ₹. 30
On final call ₹. 10


A shareholder holding 200 shares did not pay final call. His shares were forfeited. Out of these 150 shares were reissued to Ms. Sonia at ₹. 75 per share.


Give journal entries in the books of the company.

Show solutionHide solution
Worked solution
Books of Arushi Computers Ltd.
Date Particulars L.F. Debit

Amount

(₹)

Credit

Amount

(₹)

Bank A/c Dr. 2,00,000
To Share Application A/c 2,00,000
(Share Application money received for 10,000 shares @ ₹20 per share)
Share Application A/c Dr. 2,00,000
To Share Capital A/c 2,00,000
(Share Application money for 10,000 shares transferred to Share

Capital Account)

Share Allotment A/c Dr. 5,00,000
To Share Capital A/c 4,00,000
To Securities Premium Reserve A/c 1,00,000
(Allotment money due on 10,000 shares @ ₹40 per share

excluding premium ₹10)

Bank A/c Dr. 5,00,000
To Share Allotment A/c 5,00,000
(Share Allotment money received for 10,000 shares @ ₹50 per

share)

Share First Call A/c Dr. 3,00,000
To Share Capital A/c 3,00,000
(Share First Call money due on 10,000 shares @ ₹30 per share)
Bank A/c Dr. 3,00,000
To Share First Call A/c 3,00,000
(First Call money received for 10,000 shares @ ₹30 per share)
Share Final Call A/c Dr. 1,00,000
To Share Capital A/c 1,00,000
(Final Call money due on 10,000 shares @ ₹10 per share)
Bank A/c Dr. 98,000
To Share final call A/c 98,000
(Final Call money received for 9800 shares @ ₹10 per share and 200 shares failed to pay)
Share Capital A/c (200×100) Dr. 20,000
To Share Final Call A/c (200×10) 2,000
To Share Forfeiture A/c (200×90) 18,000
(200 shares forfeited for non-payment of Final Call ₹ 10 per share)
Bank A/c (150×75) Dr. 11,250
Share Forfeiture A/c (150×25) Dr. 3,750
To Share Capital A/c (150×100) Dr. 15,000
(150 forfeited shares reissued at ₹100 per share for ₹75)
Share Forfeiture A/c Dr. 9,750
To Capital Reserve A/c 9,750
(Balance of 150 reissue shares after adjustment transferred to

Capital Reserve Account)

Working Notes:

Amount Transferred to Capital Reserve A/c

Amount credited to Share Forfeiture ₹ 90 per share
Less: Amount debited to Share Forfeiture ₹25 per share
Balance after adjustment ₹ 65 per share

Amount transferred to Capital Reserve Account = Balance per share after adjustment × Number of shares reissued

₹ 9,750 = ₹ 65 × ₹ 150 per share

Q14Written answer

Raunak Cotton Ltd. issued a prospectus inviting applications for 6,000 equity shares of ₹ 100 each at a premium of ₹ 20 per shares, payable as follows:


On application ₹ 20
On allotment ₹ 50 (including premium)
On first call ₹ 30
On final call ₹ 20


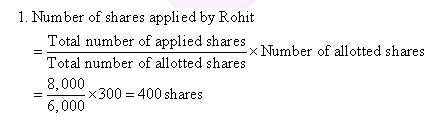
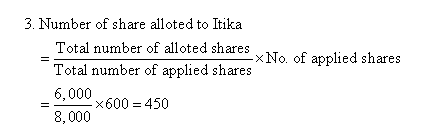
Applications were received for 10,000 shares and allotment was made Pro-rata to the applicants of 8,000 shares, the remaining applications Being refused. Money received in excess on the application was adjusted toward the amount due on allotment.


Rohit, to whom 300 shares were allotted failed to pay allotment and calls money, his shares were forfeited. Itika, who applied for 600 shares, failed to pay the two calls and her share were also forfeited. All these shares were sold to Kartika as fully paid for ₹ 80 per shares.


Give journal entries in the books of the company.

Show solutionHide solution
Worked solution
Books of Raunak Cotton Ltd.


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 2,00,000
To Share Application A/c 2,00,000
(Share Application money received on 10,000 shares)
Share Application A/c Dr. 2,00,000
To Share Capital A/c 1,20,000
To Share Allotment A/c 40,000
To Bank 40,000
(Share Application money adjusted)
Share Allotment A/c Dr. 3,00,000
To Share Capital A/c 1,80,000
To Share Premium A/c 1,20,000
(Share allotment money due)
Bank A/c Dr. 2,47,000
To Share Allotment A/c 2,47,000
(Allotment money received except 300 shares)
Share First Call A/c Dr. 1,80,000
To Share Capital A/c 1,80,000
(Share First Call money due)
Bank A/c Dr. 1,57,500
To Share First Call A/c 1,57,500
(Share First Call money received except 750 (300+450 shares)
Share Final Call A/c Dr. 1,20,000
To Share Capital A/c 1,20,000
(Share Final Call money is due)
Bank A/c Dr. 1,05,000
To Share Final Call 1,05,000
(Share Final Call money received except 750 shares)
Share Capital A/c (750×100) Dr. 75,000
Share Premium A/c (300×20) Dr. 6,000
To Share Allotment A/c 13,000
To Share first call A/c (750×30) 22,500
To Share final call A/c (750×20) 15,000
To Share Forfeiture A/c 30,500
(750 shares were forfeited)
Bank A/c Dr. 60,000
Share Forfeiture A/c Dr. 15,000
To Share Capital A/c 75,000
(Forfeited shares reissued @ 80 per share)
Share Forfeiture A/c Dr. 15,500
To Capital Reserve A/c 15,500
(Share Forfeiture Account transferred capital reserve)

Working Note:

16

2. Call in arrears by Rohit on allotment

Money received on Application (400×20) 8,000
Less: Transferred to share capital (300×20) 6,000
Excess adjusted on allotment 2,000
Allotment due (300×50) 15,000
Less: Excess adjustment on allotment 2,000
Call in arrear 13,000

17

4. Share Forfeiture amount

Amount on application
300×20 6,000
450×20 9,000
Excess amount received from Rohit for allotment on pro-rata basis 2,000
Amount received on Allotment by Kartika 13,500
30,500
Q15Written answer

Himalaya Company Limited issued for public subscription of 1, 20,000 equity shares of ₹ 10 each at a premium of ₹ 2 per share payable as under:

With Application ₹ 3 per share
On allotment (including premium) ₹ 5 per share
On First call ₹ 2 per share
On Second and Final call ₹ 2 per share

Applications were received for 1, 60,000 shares. Allotment was made on pro-rata basis. Excess money on application was adjusted against the amount due on allotment.

Rohan, whom 4,800 shares were allotted, failed to pay for the two calls. These shares were subsequently forfeited after the second call was made. All the shares forfeited were reissued to Teena as fully paid at ₹ 7 per share.

Record journal entries in the books of the company to record these transactions relating to share capital. Also show the company’s balance sheet.

Show solutionHide solution
Worked solution
Books of Himalaya Company Ltd.

Journal

Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 4,80,000
To Share Application A/c 4,80,000
(Share Application money received for 1,60,000 shares @ ₹ 3 per share)
Share Application A/c Dr. 4,80,000
To Equity Share Capital A/c 3,60,000
To Share Allotment A/c 1,20,000
(Share Application for 1,20,000 shares @ ₹ 3 per share transferred to Share Capital Account and remaining amount adjusted to Allotment)
Share Allotment A/c Dr. 6,00,000
To Equity Share Capital A/c 3,60,000
To Securities Premium 2,40,000
(Share Allotment due on 1,20,000 shares @ ₹ 5 per share including ₹ 2 Securities Premium)
Bank A/c Dr. 4,80,000
To Share Allotment A/c 4,80,000
(Share allotment for 1,20,000 shares @ ₹ 5 per share received)
Share First Call A/c Dr. 2,40,000
To Equity Share Capital A/c 2,40,000
(Share First Call due on 1,20,000 shares @ ₹ 2 per share)
Bank A/c Dr. 2,30,400
To Share First Call A/c 2,30,400
(Share First Call received on 1,15,200 shares @ ₹ 2 per share and 4,800 shares failed to pay)
Share Final Call A/c Dr. 2,40,000
To Equity Share Capital A/c 2,40,000
(Share Final call due on 1,20,000 shares @ ₹ 2 per share)
Bank A/c Dr. 2,30,400
To Share Final Call A/c 2,30,400
(Share Final Call received on 1,15,200 shares @ ₹ 2 per share and 4,800 shares failed to pay)
Equity Share Capital A/c (4,800×10) Dr. 48,000
To  Share First Call A/c (4,800×2) 9,600
To  Share Final Call A/c (4,800×2) 9,600
To  Share Forfeiture A/c (4,800×6) 28,800
(4,800 shares forfeited for the non-payment of First Call and Final Call)
Bank A/c Dr. 33,600
Share Forfeiture A/c Dr. 14,400
To  Equity Share Capital 48,000
(4,800 shares reissued @ ₹ 7 per share, fully paid-up)
Share Forfeiture A/c Dr. 14,400
To Capital Reserve A/c 14,400
(Share forfeiture balance of 4,800 shares  transferred to Capital Reserve Account)
Himalaya Company Limited
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholders’ Funds
a. Share Capital 1 12,00,000
b. Reserves and Surplus 2 2,54,400
2. Non-Current Liabilities
3. Current Liabilities
Total 14,54,400
II. Assets
1. Non-Current Assets
2. Current Assets
a. Cash and Cash Equivalents 3 14,54,400
Total 14,54,400

NOTES TO ACCOUNTS

Note No. Particulars Amount

(₹)

1 Share Capital
Authorised Share Capital
…….. shares of ₹ 10 each –
Issued Share Capital
1,20,000 shares of ₹ 10 each 12,00,000
Subscribed, Called-up and Paid-up Share Capital
1,20,000 shares of ₹ 10 each 12,00,000
2 Reserves and Surplus
Securities Premium 2,40,000
Capital Reserve 14,400 2,54,400
3 Cash and Cash Equivalents
Cash at Bank 14,54,400
Q16Written answer

Prince Limited issued a prospectus inviting applications for 20,000 equity shares of ₹. 10 each at a premium of ₹. 3 per share payable as follows:


With Application ₹. 2
On Allotment (including premium) ₹. 5
On First Call ₹. 3
On Second Call ₹. 3


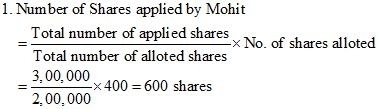
Applications were received for 30,000 shares and allotment was made on pro-rata basis. Money overpaid on applications was adjusted to the amount due on allotment.


Mr. Mohit whom 400 shares were allotted, failed to pay the allotment money and the first call, and his shares were forfeited after the first call. Mr. Joly, whom 600 shares were allotted, failed to pay for the two calls and hence, his shares were forfeited.


Of the shares forfeited, 800 shares were reissued to Supriya as fully paid for ₹. 9 per share, the whole of Mr. Mohit’s shares being included.


Record journal entries in the books of the Company and prepare the Balance Sheet.

Show solutionHide solution
Worked solution
Books of Prince Limited

Journal

Date Particulars L.F. Debit

Amount

(₹)

Credit

Amount

(₹)

Bank A/c Dr. 60,000
To Share Application A/c 60,000
(Share Application money received on 30,000 shares @₹ 2 per share)
Share Application A/c Dr. 60,000
To Share Capital A/c 40,000
To Share Allotment A/c 20,000
(Application money on 20,000 shares transferred to Share Capital Account and the balance adjusted on allotment)
Share Allotment A/c Dr. 1,00,000
To Share Capital A/c 40,000
To Securities Premium A/c 60,000
(Allotment money due on 20,000 shares @ ₹5 per share including premium of ₹ 3 per share)
Bank A/c (1,00,000 – 20,000 – 1,600) Dr. 78,400
To Share Allotment A/c 78,400
(Allotment money received)
Share First Call A/c Dr. 60,000
To Share Capital A/c 60,000
(Share First Call due on 20,000 shares @ ₹3 per share)
Bank A/c (60,000 – 1,200 – 1,800) Dr. 57,000
To Share First Call A/c 57,000
(First call money received)
Share Capital A/c Dr. 2,800
Securities Premium A/c Dr. 1,200
To Share Forfeiture A/c 1,200
To Share Allotment A/c 1,600
To Share First Call A/c 1,200
(400 shares forfeited after first call)
Share Second Call A/c Dr. 58,800
To Share Capital A/c 58,800
(Final Call money due on 19,600 shares @ ₹3 per share)
Bank A/c (58,800 – 1,800) Dr. 57,000
To Share Second Call A/c 57,000
(Second Call money received except on 600 shares)
Share Capital A/c Dr. 6,000
To Share Forfeiture A/c 2,400
To Share First Call A/c 1,800
To Share Second Call A/c 1,800
(600 shares forfeited)
Bank A/c Dr. 7,200
Share Forfeiture A/c Dr. 800
To Share Capital A/c 8,000
(800 Shares reissued @ ₹ 9 each)
Share Forfeiture A/c Dr. 2,000
To Capital Reserve 2,000

As per the Revised Schedule VI, the Balance Sheet of Prince Limited is as follows:

Prince Limited
Balance Sheet
Particulars Note No. Amount 

(₹)

I. Equity and Liabilities
1. Shareholders’ Fund
a. Share Capital 1 1,98,000
b. Reserves and Surplus 2 61,600
2. Non-Current Liabilities
3. Current Liabilities
Total 2,59,600
II. Assets
1. Non-Current Assets
2. Current Assets
a. Cash and Cash Equivalents 3 2,59,600
Total 2,59,600

NOTES TO ACCOUNTS

Note No. Particulars Amount  

(₹)

1 Share Capital
Authorised Share Capital
…….. shares of ₹10 each –
Issued Share Capital
20,000 shares of ₹10 each 2,00,000
Subscribed, Called-up and Paid-up Share Capital
19,800 shares of ₹10 each 1,98,000
2 Reserves and Surplus
Securities Premium 58,800
Capital Reserve 2,800 61,600
3 Cash and Cash Equivalents
Cash at Bank 2,59,600

Working Notes:

18

Money received on Application (600×2) 1,200
Less: Utilised on application (400×2) (800)
Excess amount received 400
Amount due on Allotment (400×5) 2,000
Less: Excess amount received (400)
Amount due on allotment 1,600

2. Amount to be transferred to Capital Reserve

Amount forfeited on Mohit’s 400 shares 1,200
Amount forfeited on Joly’s 600 shares 2,400
Amount forfeited on Joly’s 400 shares
19
1,600
2,800
Less: Discount allowed on 800 shares reissued (800)
Amount to be transferred to Capital Reserve 2,000
Q17Written answer

Life machine tools Limited, issued 50,000 equity shares of ₹ 10 each at ₹ 12 per share, payable at to ₹ 5 on application (including premium), ₹ 4 on allotment and the balance on the first and final call.

Applications for 70,000 shares had been received. Of the cash received, ₹ 40,000 was returned and ₹ 60,000 was applied to the amount due on allotment, the balance of which was paid. All shareholders paid the call due, with the exception of one share holder of 500 shares. These shares were forfeited and reissued as fully paid at ₹ 8 per share. Journalise the transactions.

Show solutionHide solution
Worked solution
Books of Life machine tools Limited


Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

  Bank A/c Dr. 3,50,000
To Share Application A/c 3,50,000
(Application money received on application for 70,000 shares @ ₹ 5 per share including premium ₹ 2)
Share Application A/c Dr. 3,50,000
To Share Capital A/c 1,50,000
To Securities Premium A/c 1,00,000
To Share Allotment A/c 60,000
To Bank A/c 40,000
(Share Application money for 50,000 shares transferred to Share

Capital Account and Securities Premium,  ₹ 60,000

adjusted to Allotment and ₹ 40,000 returned)

Share Allotment A/c Dr. 2,00,000
To Share Capital A/c 2,00,000
(Share Allotment money due on 50,000 shares @ ₹ 4 per share)
Bank A/c Dr. 1,40,000
To Share Allotment A/c 1,40,000
(Share Allotment money received on share allotment)
Share First and Final A/c Dr. 1,50,000
To Share Capital A/c 1,50,000
(Share First and Final Call money due on 50,000 shares @ ₹ 3 per share)
Bank A/c Dr. 1,48,500
To Share First and Final A/c 1,48,500
(Share First and Final Call money received from 49,500 shares @ ₹ 3 per share and 500 shares failed to pay)
Share Capital A/c (500×10) Dr. 5,000
To Share First and Final Call A/c (500×3) 1,500
To Share Forfeiture A/c (500×7) 3,500
(500 shares @ ₹ per share fully paid up forfeited for the non-

payment of Share First and Final Call ₹ 3 per share)

Bank A/c Dr. 4,000
Share Forfeiture A/c Dr. 1,000
To Share Capital A/c 5,000
(500 Shares reissued @ 8 per share fully paid up)
Share Forfeiture A/c Dr. 2,500
To Capital Reserve A/c 2,500
(Balance of 500 shares in Forfeiture Account after

adjustment, transferred to Capital Reserve Account)

Q18Written answer

The Orient Company Limited offered for public subscription 20,000 equity shares of ₹ 10 each at a premium of 10% payable at ₹ 2 on application; ₹ 4 on allotment including premium; ₹ 3 on First Call and ₹ 2 on Second and Final call. Applications for 26,000 shares were received. Applications for 4,000 shares were rejected. Pro-rata allotment was made to the remaining applicants. Both the calls were made and all the money were received except the final call on 500 shares which were forfeited. 300 of the forfeited shares were later on issued as fully paid at ₹ 9 per share. Give journal entries and prepare the balance sheet.

Show solutionHide solution
Worked solution
Books of Orient Company Limited

Journal

Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Bank A/c Dr. 52,000
To Share Application A/c 52,000
(Share Application Money received for 26,000 shares

@ ₹ 2 per share)

Share Application A/c Dr. 52,000
To Share Capital A/c 40,000
To Share Allotment A/c 4,000
To Bank A/c 8,000
(Application money  @ ₹ 2 per share of 20,000 shares

transferred to Share Capital Account and money of 4,000 shares returned, remaining to Share Allotment)

Share Allotment A/c Dr. 80,000
To Share Capital A/c 60,000
To Securities Premium A/c 20,000
(Share Allotment money due on 20,000 shares @ ₹ 4 per share including Re 1 Securities Premium)
Bank A/c Dr. 76,000
To Share Allotment A/c 76,000
(Share Allotment Money received for all the shares after

adjustment of money transferred from Share Application)

Share First Call A/c Dr. 60,000
To Share Capital A/c 60,000
(Share First Call money due on 20,000 share @ ₹ 2 per share)
Bank A/c Dr. 60,000
To Share First Call A/c 60,000
(Share First Call received for 20,000 shares @ ₹ 2 per share)
Share Second and Final Call A/c Dr. 40,000
To Share Capital A/c 40,000
(Share Second and Final  Call money due on 20,000 shares @ ₹ 2 per share)
Bank A/c Dr. 39,000
To Share Second and Final Call A/c 39,000
(Share Second and Final Call money received for 19,500 shares @ ₹ 2 per share and 500 shares failed to pay)
Share Capital A/c Dr. 5,000
To Share Second and Final Call A/c 1,000
To Share Forfeiture A/c 4,000
(500 shares  of ₹ 10 per share fully called-up forfeited for

non-payment of Second and Final Call ₹ 2 per share)

Bank A/c Dr. 2700
Share Forfeiture A/c Dr. 300
To Share Capital A/c 3,000
(300 shares @ ₹ 10 each reissued for ₹ 9 per share fully paid-up)
Share Forfeiture A/c Dr. 2,100
To Capital Reserve A/c 2,100
(Balance of 300 shares in Share Forfeiture Account transferred

to Capital Reserve Account, after adjustment)

Orient Company Limited
Balance Sheet
Particulars Note No. Amount

(₹)

I. Equity and Liabilities
1. Shareholders’ Funds
a. Share Capital 1 1,99,600
b. Reserves and Surplus 2 22,100
2. Non-Current Liabilities
3. Current Liabilities
Total 2,21,700
II. Assets
1. Non-Current Assets
2. Current Assets
  1. Cash and Cash Equivalents
3 2,21,700
Total 2,21,700

NOTES TO ACCOUNTS

Note No. Particulars Amount

(₹)

1 Share Capital
Authorised Equity Share Capital
…….. Equity Shares of ₹ 10 each –
Issued Equity Share Capital
20,000 Equity Shares of ₹ 10 each 2,00,000
Subscribed, Called-up and Paid-up Equity Share Capital
19,800 Equity Shares of ₹ 10 each 1,98,000
Add: Shares Forfeiture 1,600 1,99,600
2 Reserves and Surplus
Securities Premium 20,000
Capital Reserve 2,100 22,100
3 Cash and Cash Equivalents
Cash at Bank 2,21,700

Working Notes:

Share Forfeiture Account  credited ₹ 8 per share
Less: Share Forfeiture Account debited ₹ 1 per share
Amount  transferred to Capital Reserve Account, after adjustment ₹ 7 per share

Amount transferred to Capital Reserve Account, after adjustment for 300 shares = 300 Shares @ ₹ 7 per share = ₹ 2,100

Q19Written answer

Alfa Limited invited applications for 4, 00,000 of its equity shares of ₹ 10 each on the following terms:


Payable on application ₹ 5 per share
Payable on allotment ₹ 3 per share
Payable on first and final call ₹ 2 per share


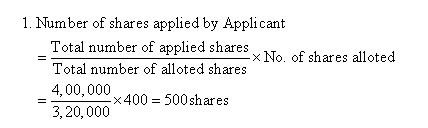
Applications for 5, 00,000 shares were received. It was decided:


(a) to refuse allotment to the applicants for 20,000 shares;

(b) to allot in full to applicants for 80,000 shares;

(c) to allot the balance of the available shares’ pro-rata among the other applicants; and

(d) to utilise excess application money in part as payment of allotment money.

One applicant, whom shares had been allotted on pro-rata basis, did not pay the amount due on allotment and on the call, and his 400 shares were forfeited. The shares were reissued @ ₹ 9 per share. Show the journal and prepare Cash book to record the above.

Show solutionHide solution
Worked solution
In the books of Alfa Limited

Journal

Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Share Application A/c Dr. 24,00,000
To Share Capital A/c 20,00,000
To Share Allotment A/c 4,00,000
(Share Application money adjusted)
Share Allotment A/c Dr. 12,00,000
To Share Capital A/c 12,00,000
(Share Allotment money due)
Share First and Final Call A/c Dr. 8,00,000
To Share Capital A/c 8,00,000
(Share First and Final Call due)

Working Note:

20

2. Call in arrears by applicant on allotment

Money received on Application (500×5) = 2,500
Less: Amount adjusted on Application (400×5) = 2,000
Amount adjusted on Allotment 500

3.

Money due on Allotment (400×3) 1,200
Less: Money adjusted 500
Balance due on Allotment 700
Date Particulars L.F. Debit

Amount

₹

Credit

Amount

₹

Share Capital A/c Dr. 4,000
To Share Allotment A/c 700
To Share First & Final Call A/c 800
To Share Forfeiture A/c 2,500
(400 shares forfeited)
Share Forfeiture A/c Dr. 400
To Share Capital A/c 400
(Share reissued and loss on issue charged from Share Forfeiture

Account)

Share Forfeiture A/c Dr. 2,100
To Capital Reserve A/c 2,100
(Share Forfeiture Account transferred to Capital Reserve Account)
Cash Book (Bank Column)
Dr. Cr.
Date Particulars J.F. Amount

₹

Date Particulars J.F. Amount

₹

Share Application 25,00,000 Share Application 1,00,000
Share Allotment 7,99,300 Balance c/d 40,02,100
Share First and Final Call 7,99,200
Share Capital 3,600
41,02,100 41,02,100


Q20Written answer

Ashoka Limited Company which had issued equity shares of ₹.20 each at a premium of ₹. 4 per share, forfeited 1,000 shares for non-payment of final call of ₹.2 per share. 400 of the forfeited shares were reissued at ₹.14 per share out of the remaining shares of 200 shares reissued at ₹.20 per share. Give journal entries for the forfeiture and reissue of shares and show the amount transferred to capital reserve and the balance in Share Forfeiture Account.

Show solutionHide solution
Worked solution
Books of Ashoka Limited

Journal

Date Particulars L.F. Debit

Amount

(₹)

Credit

Amount

(₹)

  Share Capital A/c Dr. 20,000
To Final Call A/c 2,000
To Share Forfeiture A/c 18,000
(1,000 Shares of 20 per share forfeited for nonpayment of Share Final

Call money @ ₹2 per share)

Bank A/c (400×14) Dr. 5,600
Share Forfeiture A/c (400×6) Dr. 2,400
To Share Capital A/c 8,000
(400 shares @ ₹20 per share reissued for ₹14 per share fully

paid-up)

Bank A/c Dr. 4,000
To Share Capital A/c 4,000
(200 shares @ ₹20 per share reissued for ₹20 per share fully

paid-up)

Share Forfeiture A/c Dr. 8,400
To Capital Reserve 8,400
(Balance of 600 shares in Share Forfeiture Account transferred to

Capital Reserve Account, after reissue)

Balance in Share Forfeiture Account (18,000 – 10,800) = ₹ 7,200

Working Notes:

For 400 Shares

Share Forfeiture Account credited ₹18 per share
Less: Share Forfeiture Account debited ₹6 per share
Amount  transferred to Capital Reserve Account, after adjustment ₹12 per share

Amount of 400 shares transferred to Capital Reserve Account, after reissue

= 400 Shares @ ₹ 12 per share

= ₹ 4,800

For 200 Shares

Share Forfeiture Account credited ₹18 per share
Less: Share Forfeiture Account debited Nil
Amount  transferred to Capital Reserve Account, after adjustment ₹18 per share

Amount of 200 shares transferred to Capital Reserve Account, after reissue

= 200 Shares @ ₹ 18 per share

= ₹3,600

Total amount transferred to Capital Reserve Account for 600 shares = Capital Reserve for 400 shares + Capital Reserve for 200 shares
= 4,800 + 3,600
= ₹8,400