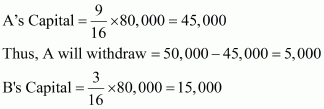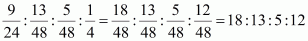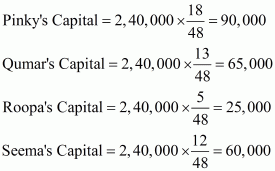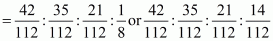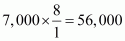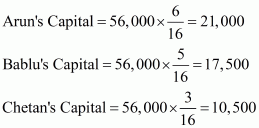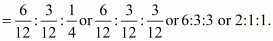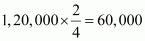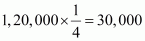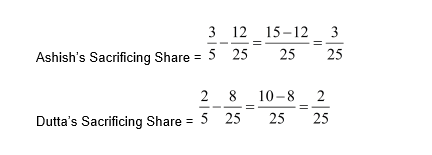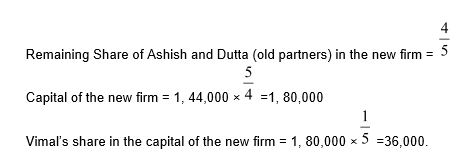My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 2: Reconstitution of a Partnership Firm – Admission of a Partner

Practice each question, then open the answer or worked solution.

Numerical Question for NCERT Accountancy Solutions Class 12 Part 1 Chapter 3

35 questions
Q31Written answer

A and B are partners sharing profits and losses in the ratio of 3:1. On 1st Jan. 2017, they admitted C as a new partner for 1/4 share in the profits of the firm. C brings ₹ 20,000 as for his 1/4 share in the profits of the firm. The capitals of A and B, after all adjustments in respect of goodwill, revaluation of Liabilities and Assets, etc., have been worked out at ₹ 50,000 for A and ₹ 12,000 for B. It is agreed that the partner’s capital will be according to the new profit-sharing ratio. Calculate the new capitals of A and B and pass the necessary journal entries assuming that A and B brought in or withdrew the necessary cash, as the case may be, for making their capitals in proportion to their profit-sharing ratio.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Books of A, B and C

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2017
Jan. 01 A’s Capital A/c  Dr. 5,000
To Cash A/c 5,000
(Excess capital withdrawn by A)
Cash A/c Dr. 3,000
To B’s Capital A/c 3,000
(Capital brought in by B to make in proportion to the profit sharing)

1) Calculation of New Profit sharing Ratio
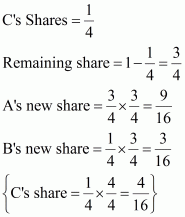
NCERT Act Class 12 Chp 3-95

New Profit sharing ratio of A, B and C will be 9:3:4

2) New Capital of A and B.

C bring ₹ 20,000 for 1/4th share of profit in the new firm.

Thus, the total capital of the firm on the basis of C’s share=
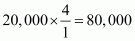
NCERT Act Class 12 Chp 3-96

NCERT Act Class 12 Chp 3-97

Thus, B’s will bring 15,000 − 12,000 = 3,000
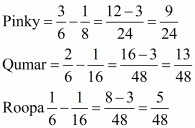
Q32Written answer

Pinky, Qumar and Roopa are partners in a firm, sharing profits and losses in the ratio of 3:2:1. S is admitted as a new partner for 1/4 share in the profits of the firm, which he gets 1/8 from Pinky, and 1/16 each from Qmar and Roopa. The total capital of the new firm after Seema’s admission will be ₹ 2, 40,000. Seema is required to bring in cash equal to 1/4 of the total capital of the new firm. The capitals of the old partners also have to be adjusted in proportion to their profit-sharing ratio. The capitals of Pinky, Qumar and Roopa after all adjustments in respect of goodwill and revaluation of Liabilities and Assets have been made are Pinky ₹ 80,000, Qumar ₹ 30,000 and Roopa ₹ 20,000. Calculate the capitals of all the partners and record the necessary journal entries for making adjustments in respect of capitals according to the agreement between the partners.

The solution to this question is as follows:

1) Calculation of new profit sharing Ratio = Old Ratio − Sacrificing Ratio

NCERT Act Class 12 Chp 3-98

New profit-sharing ratio between Pinky, Qumar, Roopa and Seema

NCERT Act Class 12 Chp 3-99

2) Required capital of all partners in the new firm

NCERT Act Class 12 Chp 3-100

3) Amount to be brought by each partner

Pinky = 90,000 − 80,000 = 10,000

Qumar = 65,000 − 30,000 = 35,000

Roopa = 25,000 − 20,000 = 5,000

Seema = 2,40,000
https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14890/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_5679cb74.gif
https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14890/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_682bd651.gif=60,000

Books of Pinky, Qumar, Roopa and Seema

Journal

Date Particulars L.F. Amount

₹

Amount

₹

Bank A/c Dr. 60,000
To Seema Capital A/c 60,000
(Seema brings her share of Capital for 1/4 th share of profit)
Bank A/c Dr. 50,000
To Pinky’s Capital A/c 10,000
To Qumar’s Capital A/c 35,000
To Roopa’s Capital A/c 5,000
(Amount brought by Pinky, Qumar and Roopa to make capital

equal to their proportion)


Show solutionHide solution
Worked solution

Solution coming soon.

Q33Written answer

The following was the Balance Sheet of Arun, Bablu and Chetan, sharing profits and losses in the ratio of respectively.

Liabilities Amount

(₹)

Assets Amount

(₹)

Creditors 9,000 Land and Buildings 24,000
Bills Payable 3,000 Furniture 3,500
Capital Accounts Stock 14,000
Arun 19,000 Debtors 12,600
Bablu 16,000 Cash 900
Chetan 8,000 43,000
    55,000   55,000
         

They agreed to take Deepak into partnership and give him a share of 1/8 on the following terms:

(a) That Deepak should bring in ₹ 4,200 as goodwill and ₹ 7,000 as his Capital;

(b) That furniture be depreciated by 12%;

(c) That stock be depreciated by 10%;

(d) That a Reserve of 5% be created for doubtful debts;

(e) That the value of land and buildings having appreciated be brought up to ₹ 31,000;

(f) That after making the adjustments, the capital accounts of the old partners (who continue to share in the same proportion as before) be adjusted on the basis of the proportion of Deepak’s Capital to his share in the business, i.e., actual cash to be paid off to, or brought in by the old partners as the case may be.


Prepare Cash Account, Profit and Loss Adjustment Account (Revaluation Account) and the Opening Balance Sheet of the new firm.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Books of Arun, Bablu, Chetan and Deepak

Profit and Loss Adjustment Account

(Revaluation Account)

Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Furniture 420 Land and Buildings 7,000
Stock 1,400
Reserve for Doubtful Debts 630
Profit on revaluation
Profit transferred to
Arun’s Capital 1,950
Bablu’s Capital 1,625
Chetan’s Capital 975 4,550
7,000 7,000
Cash Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Balance b/d 900 Arun’s Capital 1,750
Chetan’s Capital 625 Bablu’s Capital 1,625
Deepak’s Capital 7,000 Balance c/d 9,350
Premium for Goodwill 4,200
12,725 12,725
Balance Sheet
Liabilities Amount

(₹)

Assets Amount

(₹)

Creditors 9,000 Land and Buildings 31,000
Bills Payable 3,000 Furniture 3,080
Capital Account Stock 12,600
Arun 21,000 Debtor 12,600
Bablu 17,500 Less: Reserve for Doubtful Debt 630 11,970
Chetan 10,500 Cash 9,350
Deepak 7,000 56,000
  68,000     68,000
         

Working Note:

1)

Partner’s Capital Account
Dr. Cr.
Particulars Arun Bablu Chetan Deepak Particulars Arun Bablu Chetan Deepak
Bank 1,750 1,625 Balance b/d 19,000 16,000 8,000
Balance c/d 21,000 17,500 10,500 7,000 Cash A/c 7,000
Premium for goodwill 1,800 1,500 900
Revaluation 1,950 1,625 975
Bank 625
22,750 19,125 10,500 7,000 22,750 19,125 10,500 7,000

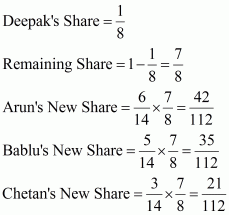
2) Calculation of New Profit Sharing Ratio

NCERT Act Class 12 Chp 3-101

New Profit sharing ratio of Arun, Bablu, Chetan and Deepak

NCERT Act Class 12 Chp 3-102

= 42:35:21:14 or 6:5:3:2

3) Calculation of capital of Arun, Bablu, and Chetan in the new firm

Deepak bring ₹ 7,000 for
NCERT Act Class 12 Chp 3-103 th share of profit.

Hence total capital of the new firm =
NCERT Act Class 12 Chp 3-104

NCERT Act Class 12 Chp 3-105

Q34Written answer

Azad and Babli are partners in a firm, sharing profits and losses in the ratio of 2:1. Chintan is admitted into the firm with 1/4 share in profits. Chintan will bring in ₹ 30,000 as his capital, and the capitals of Azad and Babli are to be adjusted in the profit-sharing ratio. The Balance Sheet of Azad and Babli as on December 31, 2016 (before Chintan’s admission) was as follows:

Balance Sheet of A and B as on 31.12.2016
Liabilities Amount

(₹)

Assets Amount

(₹)

Creditors 8,000 Cash in hand 2,000
Bills payable 4,000 Cash at bank 10,000
General reserve 6,000 Sundry debtors 8,000
Capital accounts: Stock 10,000
Azad 50,000 Furniture 5,000
Babli 32,000 82,000 Machinery 25,000
Buildings 40,000
1,00,000 1,00,000

It was agreed that:

i) Chintan will bring in ₹ 12,000 as his share of the goodwill premium.

ii) Buildings were valued at ₹ 45,000 and Machinery at ₹ 23,000.

iii) A provision for doubtful debts is to be created @ 6% on debtors.

iv) The capital accounts of Azad and Babli are to be adjusted by opening current accounts.


Record necessary journal entries, show necessary ledger accounts and prepare the Balance Sheet after admission.

Show solutionHide solution
Worked solution
Books of Azad, Babli and Chintan

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2016
Dec 31 Bank A/c Dr. 42,000
To Chintan’s Capital A/c 30,000
To Premium for Goodwill A/c 12,000
(Chintan brought Capital and Premium for Goodwill for 1/4

share of profit)

Premium for Goodwill A/c Dr. 12,000
To Azad’s Capital A/c 8,000
To Babli’s Capital A/c 4,000
(Goodwill brought by Chintan transferred to old partners

capital account in their sacrificing ratio, 2:1)

General Reserve A/c Dr. 6,000
To Azad’s Capital A/c 4,000
To Babli’s Capital A/c 2,000
(General reserve distributed between old partners)
Building A/c Dr. 5,000
To Revaluation A/c 5,000
(Increase in value of Building adjusted)
Revaluation A/c Dr. 2,480
To Machinery A/c 2,000
To Provision for Doubtful Debt 480
(Decrease in value of machinery adjusted and Provision for

Doubtful Debt created)

Revaluation A/c Dr. 2,520
To Azad is Capital A/c 1,680
To Babli’s Capital A/c 840
(Profit on revaluation transferred to Azad and Babli’s Capital

Account)

Azad’s Capital A/c Dr. 3,680
   To Azad’s Current A/c 3,680
(Excess of Capital transferred to current account)
Babli’s Capital A/c Dr. 8,840
To Babli’s Current A/c 8,840
(Excess of Capital transferred to current account)
Revaluation Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

To Machinery 2,000 Building 5,000
To Provision for Doubtful Debt 480
To Profit transferred to
Azad’s Capital 1,680
Babli’s Capital 840 2,520
5,000 5,000
Partner’s Capital Account
Dr. Cr.
Particulars Azad Babli Chintan Particulars Azad Babli Chintan
Current A/c 3,680 8,840 Balance b/d 50,000 32,000
Balance c/d 60,000 30,000 30,000 Bank 30,000
Premium for Goodwill 8,000 4,000
General Reserve 4,000 2,000
Revaluation 1,680 840
63680 38,840 30,000 63680 38,840 30,000
Balance Sheet as on December 31, 2006
Liabilities Amount

(₹)

Assets Amount

(₹)

Creditors 8,000 Cash in Hand 2,000
Bills Payable 4,000 Cash at Bank 52,000
Current Accounts: Sundry Debtors 8,000
Azad 3,680 Less: Provision for Doubtful debt 480 7,520
Babli 8,840 12,520 Stock 10,000
Capital Accounts: Furniture 5,000
Azad 60,000 Machinery 23,000
Babli 30,000 Building 45,000
Chintan 30,000 1,20,000
1,44,520 1,44,520

Working Note:

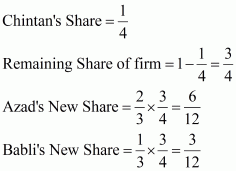
1) Calculation of New Profit Sharing Ratio

NCERT Act Class 12 Chp 3-106

New Profit sharing ratio of Azad, Babli and Chintan

NCERT Act Class 12 Chp 3-107

2) New Capital of Azad and Babli

Chintan bring ₹ 30,000 for
https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14892/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_682bd651.gifshare of profit. Hence total capital of a firm = 30,000×
NCERT Act Class 12 Chp 3-108=1, 20,000

Azad’s Capital =
NCERT Act Class 12 Chp 3-109

Babli’s Capital =
NCERT Act Class 12 Chp 3-110

Q35Written answer

Ashish and Dutta were partners in a firm, sharing profits in 3:2 ratio. On Jan. 01, 2015, they admitted Vimal for 1/5 share in the profits. The Balance Sheet of Ashish and Dutta as on Jan. 01, 2016, was as follows:


Balance Sheet of A and B as on 1.1.2016


Liabilities Amount

₹

Assets Amount

₹

Creditors 15,000 Land & Building 35,000
Bills Payable 10,000 Plant 45,000
Ashish Capital 80,000 Debtors 22,000
Dutta’s Capital 35,000 Less: Provision 2,000 20,000
Stock 35,000
Cash 5,000
  1,40,000 1,40,000
       

It was agreed that:

i) The value of Land and Building be increased by ₹ 15,000.

ii) The value of the plant be increased by 10,000.

iii) Goodwill of the firm be valued at ₹ 20,000.

iv) Vimal to bring in capital to the extent of 1/5th of the total capital of the new firm.


Record the necessary journal entries and prepare the Balance Sheet of the firm after Vimal’s admission.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Books of Ashish, Dutta and Vimal

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2016
Jan 1 Land and Building A/c Dr. 15,000
Plant A/c Dr. 10,000
To Revaluation A/c 25,000
(Increased in the value of assets)
Revaluation A/c Dr. 25,000
To Ashish’s Capital A/c 15,000
To Dutta’s Capital A/c 10,000
(Profit on revaluation transferred to partners’ capital account)
Cash A/c Dr. 36,000
To Vimal Capital A/c 36,000
(Capital brought by Vimal)
Vimal’s Current A/c Dr. 4,000
To Ashish’s Capital A/c 2,400
To Dutta’s Capital A/c 1,600
(Vimal’s share goodwill adjusted through his current account)
Balance Sheet as on January 01, 2016


Liabilities Amount

₹

Assets Amount

₹

Creditors 15,000 Land and Building 50,000
Bills Payable 10,000 Plant 55,000
Debtors 22,000
Ashish’s Capital Account 97,400 Less: Provision 2,000 20,000
Dutta’s Capital Account 46,600 Stock 35,000
Vimal’s Capital Account 36,000 Cash 41,000
Vimal’s Current Account 4,000
  2,05,000   2,05,000
   

1) Working Note:

Partners’ Capital Account
Dr. Cr.
Particulars Ashish Dutta Vimal Particulars Ashish Dutta Vimal
Balance b/d 80,000 35,000
Revaluation 15,000 10,000
Balance c/d 97,400 46,600 36,000 Cash 36,000
Vimal Current 2,400 1,600
97,400 46,600 36,000 97,400 46,600 36,000

2)

Vimal Current Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Ashish’s Capital A/c 2,400
Dutta’s Capital A/c 1,600 Balance c/d 4,000
4,000 4,000

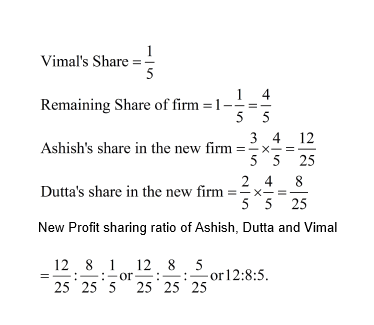
3) Calculation of New Profit Sharing Ratio

NCERT Act Class 12 Chp 3-111

4) Sacrificing Ratio = Old Ratio – New Ratio

NCERT Act Class 12 Chp 3-112

Sacrificing Ratio between Ashish and Dutta is 3:2

Note: Here, Goodwill has been adjusted through the current account because Vimal has not brought his share of goodwill, and he is to bring capital in proportion to the total capital of the new firm after adjustment.

5) Capital of new firm on the basis of old partners’ adjusted capital

Total adjusted capital of old partners

Ashish’s Capital = 97,400
Dutta’s Capital = 46,600
1,44,000

NCERT Act Class 12 Chp 3-113

Concepts covered in this chapter

  • Modes of Reconstitution of a partnership
  • Admission of a new partner
  • Sacrificing Ratio
  • Goodwill
  • Adjustment of capitals
  • Change in profit sharing ratio among the existing partners
Conclusion