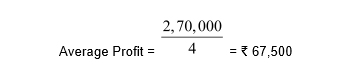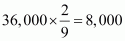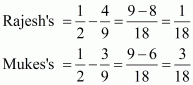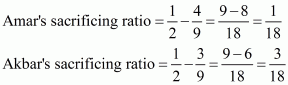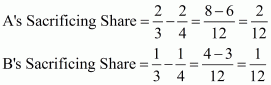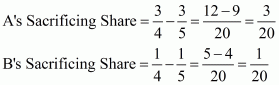My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 2: Reconstitution of a Partnership Firm – Admission of a Partner

Practice each question, then open the answer or worked solution.

Numerical Question for NCERT Accountancy Solutions Class 12 Part 1 Chapter 3

35 questions
Q21Written answer

X and Y are partners in a firm, sharing profits and losses in 4:3 ratio. They admitted Z for 1/8 share. Z brought ₹. 20,000 for his capital and ₹. 7,000 for his 1/8 share of goodwill. Subsequently X, Y and Z decided to show goodwill in their books at ₹. 40,000. Show necessary journal entries in the books of X, Y and Z.


Show solutionHide solution
Worked solution

The solution to this question is as follows:

Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
     
Cash A/c Dr. 27,000  
To Z’s Capital A/c 20,000
To Premium for Goodwill A/c 7,000
(Amount of Capital and his share of Goodwill

brought by Z)

Premium for Goodwill A/c Dr. 7,000
To X’s Capital A/c 4,000
To Y’s Capital A/c 3,000
(Premium for Goodwill credit to Old Partners in Sacrificing Ratio)  
Goodwill ₹ 40,000 cannot be raised. According to AS-10 Goodwill,

can be shown in the book if money and money value are paid for it.

Here, no money or money value has been paid for Goodwill.

Q22Written answer

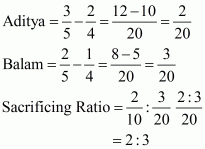
Aditya and Balan are partners sharing profits and losses in 3:2 ratio. They admitted Christopher for 1/4 share in the profits. The new profit-sharing ratio agreed upon was 2:1:1. Christopher brought ₹. 50,000 for his capital. His share of goodwill was agreed to at ₹. 15,000. Christopher could bring only ₹. 10,000 out of his share of goodwill. Record necessary journal entries in the books of the firm.

Show solutionHide solution
Worked solution

The solution to this question is as follows:


Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
Cash A/c Dr. 60,000  
To Christopher’s Capital A/c 50,000
To Premium for Goodwill A/c 10,000
(Amount of Capital and Premium for Goodwill brought by

Christopher)

Premium for Goodwill A/c Dr. 10,000
Christopher’s Capital A/c Dr. 5,000
To Adiya’s Capital A/c 6,000
To Balam’s Capital A/c 9,000
(Goodwill Christopher’s Share taken by Old Partner’s in

Sacrificing Ratio)

Sacrificing Ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-88

Q23Written answer

Amar and Samar were partners in a firm, sharing profits and losses in 3:1 ratio. They admitted Kanwar for 1/4 share of profits. Kanwar could not bring his share of the goodwill premium in cash. The Goodwill of the firm was valued at ₹. 80,000 on Kanwar’s admission. Record necessary journal entries for goodwill on Kanwar’s admission.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Amar : Samar
Old Ratio 3 : 1

Kanwar admitted for 1/4 share of profit.

Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
     
Kanwar’s Capital A/c Dr. 20,000  
To Amar’s Capital A/c 15,000
To Samar’s Capital A/c 5,000
(Kanwar’s share of goodwill charged from his capital account by

Amar and Kanwar in sacrificing ratio)

New Firm’s Goodwill = ₹ 80,000

Kanwar’s Share of Goodwill = 80,000 × (1/4) = 20,000

Kanwar’s Goodwill will be taken by Amar and Samar in their sacrificing ratio here. Sacrificing Ratio will be equal to the old ratio because the new and sacrificing ratio is not given; if sacrificing and new ratio is not given, it is assumed that the old partners sacrificed in their old ratio.

Q24Written answer

Mohan Lal and Sohan Lal were partners in a firm, sharing profits and losses in 3:2 ratio. They admitted Ram Lal for 1/4 share on 1.1.2013. It was agreed that the goodwill of the firm would be valued at 3 years’ purchase of the average profits of the last 4 years, which were ₹. 50,000 for 2013, ₹. 60,000 for 2014, ₹. 90,000 for 2015 and

₹. 70,000 for 2016. Ram Lal did not bring his share of the goodwill premium in cash. Record the necessary journal entries in the books of the firm on Ram Lal’s admission when:

a) Goodwill already appears in the books at ₹. 2, 02,500.

b) Goodwill appears in the books at ₹. 2,500.

c) Goodwill appears in the books at ₹. 2, 05,000.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Year Profit
2013 50,000
2014 60,000
2015 90,000
2016 70,000
Sum of 4 years profit 2,70,000

NCERT Act Class 12 Chp 3-89

Goodwill = Average Profit × No. of Years Purchases = 67,500 × 3 = 2, 02,500

Ram Lal entered into the firm for 1/4 share of the Profit.

Ram Lal’s share of goodwill = 2, 02, 500 × (1/4) = ₹ 50,625

Here, sacrificing ratio of Mohan Lal and Sohan Lal will be equal to the old ratio because the new and sacrificing ratio is not given.

Mohan Lal will get = Ram Lal’s Share of Goodwill × (3/5) = 50,625 × (3/5) = 10,125 × 3 = ₹ 30,375

Sohan Lal will = Ramlal Share of Goodwill × (1/5) = 50,625 × (1/5) = ₹ 10,125 × 2 = ₹ 20,250

Case (a)

Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
Mohan Lal’s Capital A/c Dr. 1,21,500  
Sohan Lal’s Capital A/c Dr. 81,000
To Goodwill A/c 2,02,500
(Goodwill appeared in the old firm written off)
Ramlal’s Capital A/c Dr. 50,625
To Mohan Lal’s Capital A/c 30,375
To Sohan Lal’s Capital A/c 20,250
(Ram Lal’s Shares of Goodwill charged  from his account

and Distributed between Mohan Lal and Sohan Lal in

Sacrificing Ratio)

Case (b)

Journal Entries
Date Particulars L.F. Debit Amount

₹

Credit Amount ₹
Mohan Lal’s Capital A/c Dr. 1,500
Sohan Lal’s Capital A/c Dr. 1,000
To Goodwill A/c 2,500
(Goodwill already appeared in the books of the firm

written off in the old ratio)

Ramlal’s Capital A/c Dr. 50,625
To Mohan Lal’s Capital A/c 30,375
To Sohan Lal’s Capital A/c 20,250
(Ram Lal’s Shares of Goodwill charged  from his

capital by Mohan Lal and Sohan Lal in sacrificing ratio)

Case (c)

Journal Entries
Date Particulars L.F. Debit Amount

₹

Credit Amount ₹
Mohan Lal’s Capital A/c Dr. 1,23,000
Sohan Lal’s Capital A/c Dr. 82,000
To Ram Lal’s Capital A/c 2,05,000
(Goodwill already appeared in the books of firm written off in Old Ratio)
Ramlal’s Capital A/c Dr. 50,625
To Mohan Lal’s Capital A/c 30,375
To Sohan Lal’s Capital A/c 20,250
(Ram Lal’s Shares of Goodwill charged  from his capital

by Mohan Lal and Sohan Lal in sacrificing ratio)

Q25Written answer

Rajesh and Mukesh are equal partners in a firm. They admit Hari into partnership, and the new profit-sharing ratio between Rajesh, Mukesh and Hari is 4:3:2. On Hari’s admission, the goodwill of the firm is valued at ₹ 36,000. Hari is unable to bring his share of the goodwill premium in cash. Rajesh, Mukesh and Hari decided not to show goodwill on their balance sheet. Record necessary journal entries for the treatment of goodwill on Hari’s admission.

Show solutionHide solution
Worked solution

The solution to this question is as follows:


Books of Rajesh, Mukesh and Hari

Journal

Date Particulars L.F. Amount

₹

Amount

₹

Hari’s Capital A/c Dr. 8,000
To Rajesh’s Capital A/c 2,000
To Mukesh’s Capital A/c 6,000
(Adjustment of Hari’s share of goodwill)

Working Notes:

1) Goodwill of a firm = 36,000

Hari’s share in the goodwill.

= Goodwill of firm × admitting Partner Share

NCERT Act Class 12 Chp 3-90

2) Sacrificing Ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-91

Sacrificing Ratio between Rajesh and Mukesh 1:3.

Q26Written answer

Amar and Akbar are equal partners in a firm. They admitted Anthony as a new partner, and the new profit-sharing ratio is 4:3:2. Anthony could not bring this share of goodwill ₹ 45,000 in cash. It is decided to do adjustments for goodwill without opening a goodwill account. Pass the necessary journal entry for the treatment of goodwill.

Show solutionHide solution
Worked solution

 The solution to this question is as follows:

Books of Amar, Akbar and Anthony

Journal

Date Particulars L.F. Amount

₹

Amount

₹

Anthony’s Capital A/c Dr. 45,000
To Amar’s Capital A/c 11,250
To Akbar’s Capital A/c 33,750
(Adjustment of Anthony’s share of goodwill between

Amar and Akbar in sacrificing ratio)

Working Notes:

1) Sacrificing Ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-92

Sacrificing Ratio between Amar and Akbar = 1:3

Q27Written answer

Given below is the Balance Sheet of A and B, who are carrying on partnership business on 31.12.2016. A and B share profits and losses in the ratio of 2:1.

Balance Sheet of A and B as on December 31, 2016


Liabilities Amount

(₹)

Assets Amount

(₹)

Bills Payable 10,000 Cash in Hand 10,000
Creditors 58,000 Cash at Bank 40,000
Outstanding 2,000 Sundry Debtors 60,000
Expenses Stock 40,000
Capitals: Plant 1,00,000
A 1,80,000 Buildings 1,50,000
B 1,50,000 3,30,000
      4,00,000 4,00,000
           

C is admitted as a partner on the date of the balance sheet on the following terms:


(i) C will bring in ₹ 1, 00,000 as his capital and ₹ 60,000 as his share of goodwill for 1/4 share in the profits.

(ii) Plant is to be appreciated to ₹ 1, 20,000 and the value of buildings is to be appreciated by 10%.

(iii) Stock is found overvalued by ₹ 4,000.

(iv) A provision for bad and doubtful debts is to be created at 5% of debtors.

(v) Creditors were unrecorded to the extent of ₹ 1,000.


Pass the necessary journal entries, prepare the revaluation account and partners’ capital accounts, and show the Balance Sheet after the admission of C.

Show solutionHide solution
Worked solution

The solution to this question is as follows:


Books of A, B and C

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2016
Dec 31 Bank A/c Dr. 1,60,000
To C’s Capital A/c 1,00,000
To Premium for Goodwill A/c 60,000
(Capital and premium for goodwill brought by C for 1/4 th share)
Premium for Goodwill A/c Dr. 60,000
To A’s Capital A/c 40,000
To B’s Capital A/c 20,000
(Premium for Goodwill brought by C transferred to old partners’ capital

account in their sacrificing ratio, 3:1)

Plant A/c Dr. 20,000
Building A/c Dr. 15,000
To Revaluation A/c 35,000
(Value of assets increased)
Revaluation A/c Dr. 8,000
To Stock 4,000
To Provision for Doubtful Debts A/c 3,000
To Creditors A/c (Unrecorded) 1,000
(Liabilities and Assets revalued)
Revaluation A/c Dr. 27,000
To A’s Capital A/c 18,000
To B’s Capital A/c 9,000
(Profit on revaluation transferred to old partners’ capital account)
Revaluation Account


Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Stock 4,000 Plant 20,000
Provision for Doubtful Debts 3,000 Building 15,000
Creditors (Unrecorded) 1,000
Profit transferred to
A’s Capital 18,000
B’s Capital 9,000 27,000
35,000 35,000
Partners’ Capital Account 
Dr. Cr.
Particulars A B C Particulars A B C
Balance c/d 2,38,000 1,79,000 1,00,000 Balance b/d 1,80,000 1,50,000
Bank 1,00,000
Premium for Goodwill 40,000 20,000
Revaluation 18,000 9,000
2,38,000 1,79,000 1,00,000 2,38,000 1,79,000 1,00,000
Balance Sheet as on December 31, 2016


Liabilities Amount

(₹)

Assets Amount

(₹)

Bills Payable 10,000 Cash in Hand 10,000
Creditors 59,000 Cash at Bank 2,00,000
Outstanding Expenses 2,000 Sundry Debtors 60,000
Capital: Less: Provision for Doubtful Debt 3,000 57,000
A 2,38,000 Stock 36,000
B 1,79,000 Plant 1,20,000
C 1,00,000 5,17,000 Building 1,65,000
  5,88,000     5,88,000
         

Working Note:

1) Sacrificing ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-92

Sacrificing ratio between A and B = 2:1.

Q28Written answer

Leela and Meeta were partners in a firm, sharing profits and losses in a ratio of 5:3. On Jan. 2017, they admitted Om as a new partner. On the date of Om’s admission, the balance sheet of Leela and Meeta showed a balance of ₹ 16,000 in general reserve and ₹ 24,000 (Cr) in the Profit and Loss Account. Record necessary journal entries for the treatment of these items on Om’s admission. The new profit-sharing ratio between Leela, Meeta and Om was 5:3:2.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Books of Leela, Meeta and Om

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2017
Jan 1 General Reserve A/c Dr. 16,000
Profit and Loss A/c Dr. 24,000
To Leela’s Capital A/c 25,000
To Meeta’s Capital A/c 15,000
(General reserve and balance in Profit and Loss credited to old

partners’ capital account in their old ratio, 5:3)

Q29Written answer

Amit and Viney are partners in a firm, sharing profits and losses in 3:1 ratio. On 1.1.2017, they admitted Ranjan as a partner. On Ranjan’s admission, the profit and loss account of Amit and Viney showed a debit balance of ₹ 40,000. Record the necessary journal entry for the treatment of the same.

Show solutionHide solution
Worked solution

The solution to this question is as follows:


Books of Amit, Viney and Ranjan

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2017
Jan 1 Amit’s Capital A/c Dr. 30,000
Viney’s Capital A/c Dr. 10,000
To Profit and Loss A/c 40,000
(Debit Balance in Profit and Loss Account written off)
Q30Written answer

A and B share profits in the proportions of 3/4 and 1/4. Their Balance Sheet on Dec. 31, 2016, was as follows.

Balance Sheet of A and B as on December 31, 2016
Liabilities Amount

(₹)

Assets Amount

(₹)

Sundry creditors 41,500 Cash at Bank 26,500
Reserve fund 4,000 Bills Receivable 3,000
Capital Accounts Debtors 16,000
A 30,000 Stock 20,000
B 16,000 Fixtures 1,000
Land & Building 25,000
91,500 91,500

On Jan. 1, 2017, C was admitted into the partnership on the following terms.


(a) That C pays ₹ 10,000 as his capital.

(b) That C pays ₹ 5,000 for goodwill. Half of this sum is to be withdrawn by A and B.

(c) That stock and fixtures be reduced by 10% and a 5% provision for doubtful debts be created on Sundry Debtors and Bills Receivable.

(d) That the value of land and buildings be appreciated by 20%.

(e) There being a claim against the firm for damages, a liability to the extent of ₹ 1,000 should be created.

(f) An item of ₹ 650 included in sundry creditors is not likely to be claimed and hence should be written back.


Record the above transactions (journal entries) in the books of the firm, assuming that the profit-sharing ratio between A and B has not changed. Prepare the new Balance Sheet on the admission of C.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Books of A, B and C

Journal

Date Particulars L.F. Amount

₹

Amount

₹

2017
Jan. 01 Bank A/c Dr. 15,000
To C’s Capital A/c 10,000
To Premium for Goodwill A/c 5,000
(Capital and Premium for goodwill brought by C

for 1/5 th share)

Jan. 01 Premium for Goodwill A/c 5,000
To A’s Capital A/c 3,750
To B’s Capital A/c 1,250
(Amount of goodwill brought by C is transferred to old

partners’ capital account in their sacrificing ratio, 3:1)

Jan. 01 A’s Capital A/c Dr. 1,875
B’s Capital A/c Dr. 625
To Bank A/c 2,500
(Half of amount  withdrawn by old partners)
Jan. 01 Revaluation A/c Dr. 4,050
To Stock A/c 2,000
To Fixture A/c 100
To Provision for doubtful Debts on Debtors A/c 800
To provision for doubtful Debts on Bills Receivable A/c 150
To Claim for Damages A/c 1,000
(Liabilities and Assets are revalued)
Jan. 01 Land and Building A/c Dr. 5,000
Sundry Creditors A/c 650
To Revaluation A/c 5,650
(Asset and liability are revalued)
Jan. 01 Revaluation A/c Dr. 1,600
To A’s Capital A/c 1,200
To B’s Capital A/c 400
(Profit on Revaluation transferred to old partners’ capital)
Jan. 01 Reserve Fund A/c Dr. 4,000
To A’s Capital A/c 3,000
To B’s Capital A/c 1,000
(Reserve Fund distributed among old partners)
Balance Sheet as on January 01, 2007
Liabilities Amount

(₹)

Assets Amount

(₹)

Sundry Creditors 40,850 Cash at Bank 39,000
Claim for Damages 1,000 Bills Receivable 3,000
A 36,075 Less: Provision 150 2,850
B 18,025 Debtors 16,000
C 10,000 64,100 Less: Provision 800 15,200
Stock 18,000
Fixtures 900
Land and Building 30,000
1,05,950 1,05,950

Working Note:

1)

Partners’ Capital Account
Dr. Cr.
Particulars A B C Particulars A B C
Bank 1,875 625 Balance b/d 30,000 16,000
Balance c/d 36,075 18,025 10,000 Bank 10,000
Premium for Goodwill 3,750 1,250
Revaluation 1,200 400
Reserve Fund 3,000 1,000
37,950 18,650 10,000 37,950 18,650 10,000

2)

Bank Account
Dr. Cr.
Particulars Amount

₹

Particulars Amount

₹

Balance b/d 26,500 A’s Capital A/c 1,875
C’s Capital A/c 10,000 B’s Capital A/c 625
Premium for Goodwill 5,000 Balance c/d 39,000
41,500 41,500

3)

Sacrificing ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-94

Note: Assuming that the ratio between A and B has not changed, hence, the sacrificing ratio should be the same as the old ratio.