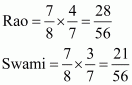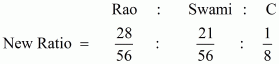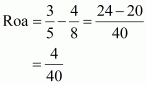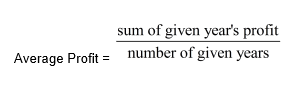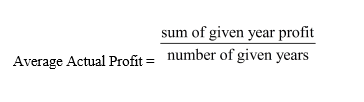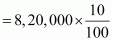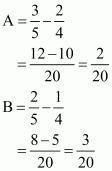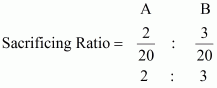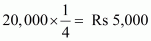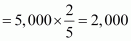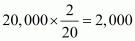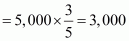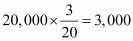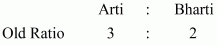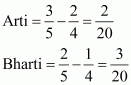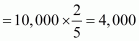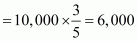My Cart
Your Cart 0

    Your cart is empty.

  • Total (Amount) ₹0.00
NCERT · Class 12 · Accountancy

Unit 2: Reconstitution of a Partnership Firm – Admission of a Partner

Practice each question, then open the answer or worked solution.

Numerical Question for NCERT Accountancy Solutions Class 12 Part 1 Chapter 3

35 questions
Q11Written answer

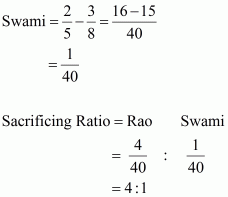
Sandeep and Navdeep are partners in a firm, sharing profits in 5:3 ratio. They admit C into the firm, and the new profit-sharing ratio was agreed at 4:2:1. Calculate the sacrificing ratio.

Show solutionHide solution
Worked solution

The solution to this question is as follows:
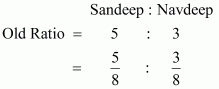
NCERT Act Class 12 Chp 3-55

NCERT Act Class 12 Chp 3-56

Sacrificing Ratio = Old Ratio − New Ratio

NCERT Act Class 12 Chp 3-57

NCERT Act Class 12 Chp 3-58

Q12Written answer

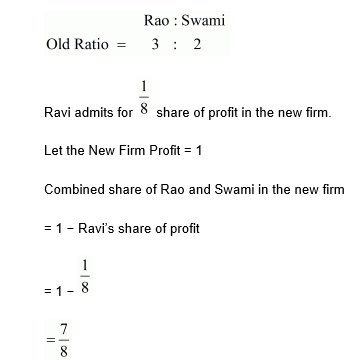
Rao and Swami are partners in a firm, sharing profits and losses in 3:2 ratio. They admit Ravi as a new partner for 1/8 share in the profits. The new profit-sharing ratio between Rao and Swami is 4:3. Calculate the new profit-sharing ratio and sacrificing ratio.

Show solutionHide solution
Worked solution

The solution to this question is as follows:
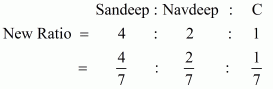
NCERT Act Class 12 Chp 3-57

New Ratio = Combined Share of Rao and Swami × Proportion of Rao and Swami in the combined share

NCERT Act Class 12 Chp 3-58

NCERT Act Class 12 Chp 3-58

NCERT Act Class 12 Chp 3-59

4:3:1

Sacrificing Ratio = Old Ratio − New Ratio
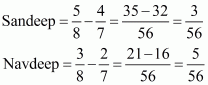
NCERT Act Class 12 Chp 3-60

NCERT Act Class 12 Chp 3-61

Q13Written answer

Compute the value of goodwill on the basis of four years’ purchase of the average profits based on the last five years? The profits for the last five years were as follows:


  ₹
2013 40,000
2014 50,000
2015 60,000
2016 50,000
2017 60,000

NCERT Act Class 12 Chp 3-62

Show solutionHide solution
Worked solution
Year Profit
2013 40,000
2014 50,000
2015 60,000
2016 50,000
2017 60,000
Sum of 5 years profit 2,60,000

Average Profit =  = 52,000

Goodwill = Average Profit × Number of Year’s Purchases = 52,000 × 4 = ₹ 2, 08,000

Q14Written answer

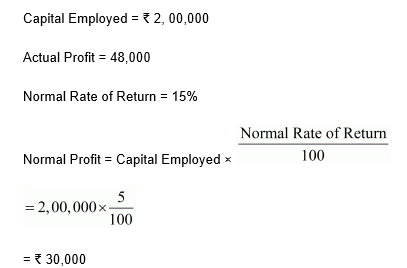
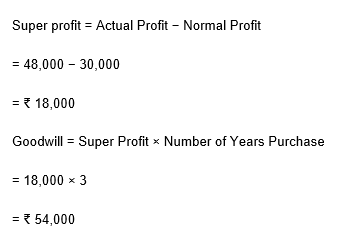
Capital employed in a business is ₹.2, 00,000. The normal rate of return on capital employed is 15%. During the year 2015, the firm earned a profit of ₹. 48,000. Calculate goodwill on the basis of 3 years’ purchase of super profit.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

NCERT Act Class 12 Chp 3-63

Q15Written answer

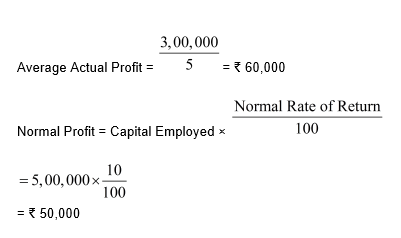
The books of Ram and Bharat showed that the capital employed on 31.12.2016 was ₹. 5,00,000 and the profits for the last 5 years: 2015 ₹. 40,000; 2014 ₹. 50,000; 2013 ₹. 55,000; 2012 ₹. 70,000 and 2011 ₹. 85,000. Calculate the value of goodwill on the basis of 3 years’ purchase of the average super profits of the last 5 years, assuming that the normal rate of return is 10%.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

NCERT Act Class 12 Chp 3-64

Year Profit
2015 40,000
2014 50,000
2013 55,000
2012 70,000
2011 85,000
Sum of 5 years profit 3,00,000

NCERT Act Class 12 Chp 3-65

Average Super Profit = Average Actual Profit – Normal Profit

= 60,000 – 50,000

= ₹ 10,000

Goodwill = Average Super Profit × Number of year purchase

= 10,000 × 3

= ₹ 30,000

Q16Written answer

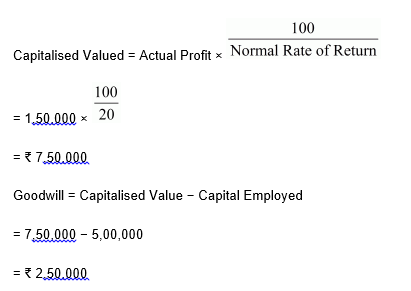
Rajan and Rajani are partners in a firm. Their capitals were Rajan ₹.3, 00,000; Rajani ₹. 2, 00,000. During the year 2015, the firm earned a profit of ₹. 1, 50,000. Calculate the value of goodwill of the firm, assuming that the normal rate of return is 20%.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Rajan’s Capital 3,00,000
Rajni’s Capital 2,00,000
Total Capital Employed 5,00,000

Normal Rate of Return = 20%

NCERT Act Class 12 Chp 3-66

Alternative Method

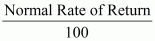
Normal Profit = Capital Employed ×
NCERT Act Class 12 Chp 3-68

= 5,00,000 ×
https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14872/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_4f8f1ff1.gif

= ₹ 1,00,000

Super profit = Actual Profit − Normal Profit

= 1, 50,000 − 1, 00,000

= ₹ 50,000

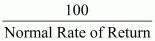
Goodwill = Super Profit ×
NCERT Act Class 12 Chp 3-69

= 50,000 ×
https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14872/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_m1cac3f38.gif

= ₹ 2, 50,000

Q17Written answer

A business has earned average profits of ₹. 1, 00,000 during the last few years. Find out the value of goodwill by capitalisation method, given that the assets of the business are ₹. 10, 00,000 and its external liabilities are ₹. 1, 80,000. The normal rate of return is 10%.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Capital Employed = Assets − External Liabilities

= 10, 00,000 − 1, 80,000

= Rs 8, 20,000

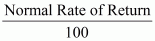
Normal Profit = Capital Employed ×
NCERT Act Class 12 Chp 3-70

NCERT Act Class 12 Chp 3-71

= Rs 82,000

Super Profit = Actual Profit − Normal Profit

= 1, 00,000 − 82,000

= Rs 18,000

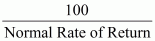
Goodwill = Super Profit ×
NCERT Act Class 12 Chp 3-72

https://img-nm.mnimgs.com/img/study_content/curr/1/15/17/2430/14873/Gr12_Acc_NCERT_Book1-Chp3_Vas_Dilpreet_html_m17bdff58.gif

= Rs 1, 80,000

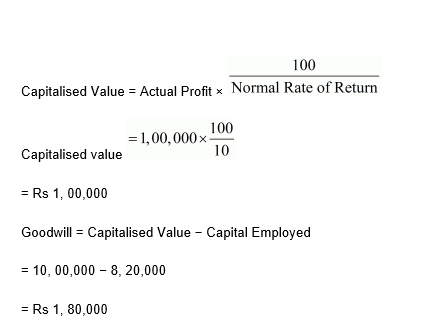
Alternative Method

NCERT Act Class 12 Chp 3-73

Q18Written answer

Verma and Sharma are partners in a firm, sharing profits and losses in the ratio of 5:3. They admitted Ghosh as a new partner for 1/5 share of profits. Ghosh is to bring in ₹. 20,000 as capital and ₹. 4,000 as his share of goodwill premium. Give the necessary journal entries.

a) When the amount of goodwill is retained in the business.

b) When the amount of goodwill is fully withdrawn.

c) When 50% of the amount of goodwill is withdrawn.

d) When goodwill is paid privately.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Journal Entries
S.No. Particulars L.F. Debit Amount ₹ Credit Amount ₹
Case (a)
Cash A/c Dr. 24,000
To Ghosh’s Capital A/c 20,000
To Premium for Goodwill A/c 4,000
(Capital and Goodwill his share brought

by Ghosh)

Premium for Godwill A/c Dr. 4,000
To Verma’s Capital A/c 2,500
To Sharma’s Capital A/c 1,500
(Goodwill brought by Ghosh credited to Old Partners

in Sacrificing ratio)

Case (b) Cash A/c Dr. 24,000
To Ghosh Capital A/c 20,000
To Premium for Goodwill A/c 4,000
(Capital and Goodwill brought by Ghosh for (1/5)

share of profit)

Premium for Goodwill A/c Dr. 4,000
To Verma’s Capital A/c 2,500
To Sharma’s Capital A/c 1,500
(Goodwill brought by Ghosh credited

in Old  Partner in Sacrificing Ratio)

Verma’s Capital A/c Dr. 2,500
Sharma’s Capital A/c Dr. 1,500
To Cash A/c 4,000
(Amount of Premium for Goodwill withdrawn by

Old Partners)

Case (c) Cash A/c Dr. 24,000
To Ghosh’s Capital A/c 20,000
To Premium for Goodwill A/c 4,000
(Capital and Goodwill brought by Ghosh for (1/5)

share of profit)

Premium for Goodwill A/c Dr. 4,000
To Verma’s Capital A/c 2,500
To Sharma’s Capital A/c 1,500
(Premium for Goodwill credited to Old Partner’s

Captial Account in sacrificing ratio)

Verma’s Capital A/c Dr. 1,250
Sharma’s Capital A/c 750
To Cash A/c 2,000
(Half of the amount of premium for goodwill  withdrawn by Old partners)
Case (d) No entry: Goodwill was not brought into firm
Q19Written answer

A and B are partners in a firm, sharing profits and losses in the ratio of 3:2. They decide to admit C into partnership with 1/4 share in profits. C will bring in ₹. 30,000 for capital and the requisite amount of goodwill premium in cash. The goodwill of the firm is valued at ₹, 20,000. The new profit-sharing ratio is 2:1:1. A and B withdraw their share of goodwill. Give necessary journal entries.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
     
Cash A/c Dr. 35,000  
To C’s Capital A/c 30,000
To Premium for Goodwill A/c 5,000
(Amount of Capital and Share of Goodwill brought by C)
Premium for Goodwill A/c Dr. 5,000
To A’s Capital A/c 2,000
To B’s Capital A/c 3,000
(C’s Share of Goodwill credited to A and B in 2:3,

Sacrificing Ratio)

 
A’s Capital A/c Dr. 2,000
B’s Capital A/c Dr. 3,000
To Cash A/c 5,000
(Share of Goodwill withdrawn by Old  Partners)

Sacrificing Ratio = Old Ratio − New Ratio
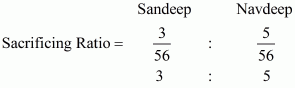
NCERT Act Class 12 Chp 3-74

NCERT Act Class 12 Chp 3-75

Goodwill of the firm = Rs 20,000

C’s share of Goodwill =
NCERT Act Class 12 Chp 3-76

A will receive
NCERT Act Class 12 Chp 3-77

Or
NCERT Act Class 12 Chp 3-78

B will receive
NCERT Act Class 12 Chp 3-80

Or
NCERT Act Class 12 Chp 3-81

Q20Written answer

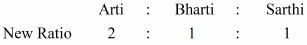
Arti and Bharti are partners in a firm, sharing profits in 3:2 ratio; they admitted Sarthi for 1/4 share in the profits of the firm. Sarthi brings ₹. 50,000 for his capital and ₹. 10,000 for his 1/4 share of goodwill. Goodwill already appears in the books of Arti and Bharti at ₹. 5,000. The new profit-sharing ratio between Arti, Bharti and Sarthi will be 2:1:1. Record the necessary journal entries in the books of the new firm.

Show solutionHide solution
Worked solution

The solution to this question is as follows:

Journal Entries
Date Particulars L.F. Debit Amount ₹ Credit Amount ₹
     
Arti’s Capital A/c Dr. 3,000  
Bharti’s Capital A/c Dr. 2,000
To Goodwill A/c 5,000
(Goodwill written off)
Cash A/c Dr. 60,000
To Sarthi’s Capital A/c 50,000
To Premium for Goodwill A/c 10,000
(Amount of capital and share of goodwill brought by Sarthi)  
Premium for Goodwill A/c Dr. 10,000
To Arti’s Capital A/c 4,000
To Bharti’s Capital A/c 6,000
(Premium for Goodwill credited Arti’s Capital Account)

NCERT Act Class 12 Chp 3-82

Sarthi admitted for
NCERT Act Class 12 Chp 3-82 share in a new firm.

NCERT Act Class 12 Chp 3-83

Sacrificing Ratio = Old Ratio − New Ratio
NCERT Act Class 12 Chp 3-84

Arti will receive
NCERT Act Class 12 Chp 3-85

Bharti will receive
NCERT Act Class 12 Chp 3-86